
Close Menu
Aspire Market Guides
  • Home
  • Alternative Investments
  • Cryptocurrency
  • Economics
  • Equity Investments
  • Mutual Funds
  • Real Estate
  • Trading
What's Hot

Baillie Gifford Opens Tokenised Bond Fund in Four Markets

September 30, 2026

Hedge fund Point72 hired the former head of JPMorgan’s equities central risk book

September 30, 2026

Should You Buy Solana or Bitcoin With $1,000?

September 30, 2026
Facebook X (Twitter) Instagram
Trending:
  • Baillie Gifford Opens Tokenised Bond Fund in Four Markets
  • Hedge fund Point72 hired the former head of JPMorgan’s equities central risk book
  • Should You Buy Solana or Bitcoin With $1,000?
  • Ethiopia’s Macroeconomic Reform Delivers Concrete Results in Easing Debt Burden: Finance Minister – ENA English
  • Silver Price Forecast: XAG/USD remains vulnerable near $60
  • Senate to vote on stock trading ban, data center bill before election recess
  • Manufacturers or money managers? Consumer goods firms hold N587 billion cash in 2026
  • FCA Opens Five-Month Authorisation Window for UK Crypto Firms – Finance Magnates
  • Silver Price Forecast: $61 in Focus as Sellers Await Fresh US Inflation Data
  • Situational Awareness hedge fund collapse reveals record leverage
Wednesday, September 30
Facebook X (Twitter) Instagram
Aspire Market Guides
  • Home
  • Alternative Investments
  • Cryptocurrency
  • Economics
  • Equity Investments
  • Mutual Funds
  • Real Estate
  • Trading
Aspire Market Guides
Home»Economics»Inflation, rising interest rates and high levels of debt. A new macroeconomic regime has emerged
Economics

Inflation, rising interest rates and high levels of debt. A new macroeconomic regime has emerged

By CharlotteSeptember 30, 20264 Mins Read
Share
Facebook Twitter Pinterest Email Copy Link


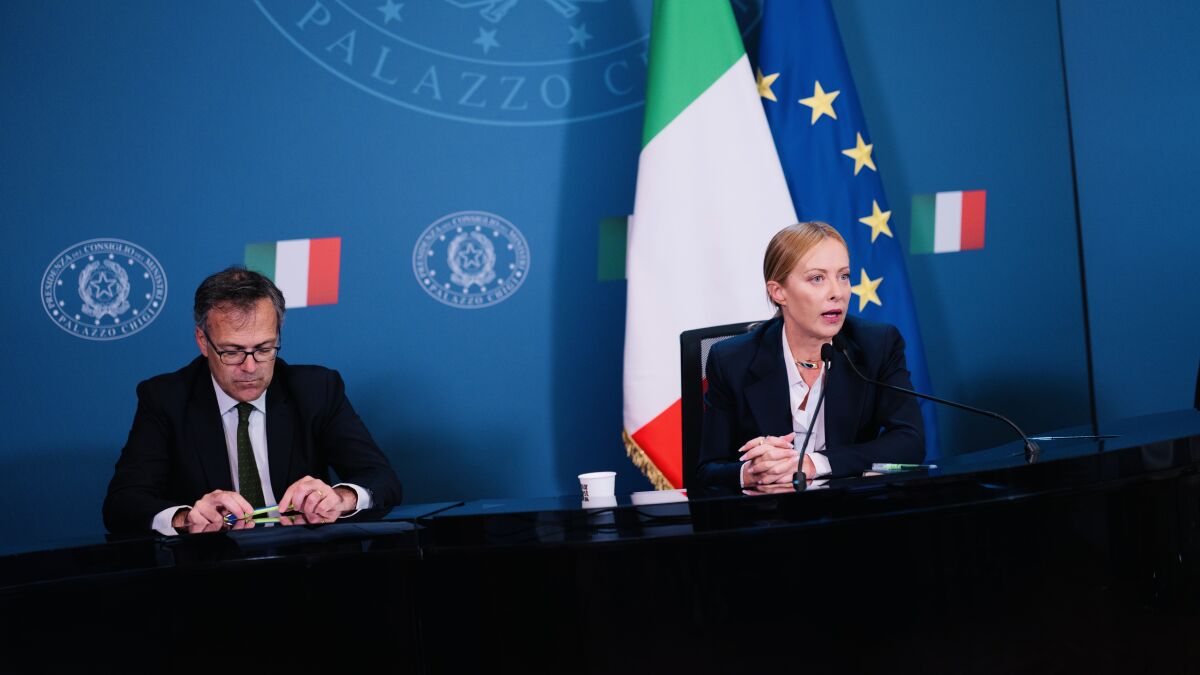
Italy’s 2025 deficit remained at 3.1 per cent of GDP. That decimal point above 3 per cent prevented an early exit from the European excessive deficit procedure and immediately reignited the debate over the few billion in ‘flexibility’ that would thus be missing from the next budget.

Yet this approach resembles seeing the speck in someone else’s eye while overlooking the log in one’s own. Debating a few billion more or less to be spent risks obscuring the far more significant change that has taken place in the international macroeconomic landscape. With public debt standing at 137 per cent of GDP, Italy’s budgetary constraints are now much tighter, not so much because of pressure from Brussels but because market conditions have changed profoundly.

For over a decade, we have become accustomed to very low inflation, interest rates close to zero and central banks acting as major buyers of government bonds. Under those conditions, even high levels of debt seemed relatively easy to manage. Today, this is no longer the case. Inflation has not yet returned to target on a stable basis in many countries; interest rates are higher; central banks are reducing their bond portfolios; and the major investment cycle linked to artificial intelligence is competing with governments for available savings. At the same time, the gross public debt of advanced economies has risen to nearly 110 per cent of GDP, compared with around 70 per cent in the early 2000s. In September, the median yield on 10-year government bonds in advanced economies exceeded 4 per cent, around five times the average for 2015–21. Higher debt levels are now meeting higher interest rates. And the long end of the yield curve has become more volatile.

For Italy, this matters a great deal. Debt stood at 137.1 per cent at the end of 2025, and the European Commission forecasts it will rise to 139.2 per cent in 2027. The higher cost of borrowing is not immediately passed on to the entire debt stock, as the average remaining maturity of the debt is long – around 7.9 years. However, nearly 600 billion, about a fifth of the total, has a residual maturity of less than one year and will therefore have to be refinanced at prevailing market rates. Interest expenditure stands at 3.9 per cent of GDP in 2025, the second highest in the G7 after that of the United States.

The Economist reports that if all the debt were to be refinanced today at current five-year yields, the UK would need a primary surplus of 1.5 per cent of GDP just to stabilise its debt-to-GDP ratio. Italy would follow closely behind, at 1.4 per cent, ahead of France (1.2 per cent) and the United States (1 per cent). It is a purely hypothetical scenario, but it clearly illustrates how much the arithmetic of debt has changed compared with the years of zero interest rates. Yet we often continue to talk about the fiscal constraint as if it were primarily a European rule. The 3 per cent figure is a rule. A debt-to-GDP ratio of 137 per cent and the rate at which investors are willing to refinance it are economic constraints in their own right.

Reducing a debt of this magnitude is neither simple nor quick. It takes years, a credible strategy and, above all, economic growth. The solution cannot be to seek growth through yet another permanent expansion of debt-financed public spending. That would amount to trying to solve the debt problem by taking on more debt. In 2025, public sector spending stood at around 51 per cent of GDP, compared with around 47 per cent twenty years ago. So much for the much-vaunted austerity. The decisive factor is potential growth: productivity, private investment, human capital, competition, the size of businesses and the functioning of institutions. As we often repeat in these columns, genuine supply-side policies are needed – policies that increase the country’s capacity to produce without having to continually prop up demand with new deficits.

This is also why the issue should feature in the upcoming election campaign. As always, promises of new spending or tax cuts are beginning to emerge, whilst the funding arrangements tend to be far less visible. Alongside the tables listing what is promised to be distributed, it would be useful to publish another: debt-to-GDP ratio, primary balance and projected growth for the next five years, together with the measures intended to achieve it.

It is a much less popular table than the one showing bonuses. But, ultimately, it is the one that needs to be included.


Source link

Related Posts

Economics

Ethiopia’s Macroeconomic Reform Delivers Concrete Results in Easing Debt Burden: Finance Minister – ENA English

September 30, 2026
Economics

Where Do Economists Work? | SNHU

September 30, 2026
Economics

UK Economic Development and Real Estate launches Kentucky Economic Opportunity Map

September 30, 2026
Economics

Thai businesses tap Indonesian market as domestic opportunities shrink – Economy

September 30, 2026
Economics

El Nino to worsen LatAm’s economic woes, warns Chilean expert-Xinhua

September 30, 2026
Economics

Update: US Equity Indexes Fall as Markets Parse Mixed Macroeconomic Data

September 29, 2026
Add A Comment
Leave A Reply Cancel Reply

Editors Picks

Baillie Gifford Opens Tokenised Bond Fund in Four Markets

September 30, 2026

Hedge fund Point72 hired the former head of JPMorgan’s equities central risk book

September 30, 2026

Should You Buy Solana or Bitcoin With $1,000?

September 30, 2026

Ethiopia’s Macroeconomic Reform Delivers Concrete Results in Easing Debt Burden: Finance Minister – ENA English

September 30, 2026
SUBSCRIBE TO OUR NEWSLETTER

Get our latest downloads and information first. Complete the form below to subscribe to our weekly newsletter.


I consent to being contacted via telephone and/or email and I consent to my data being stored in accordance with European GDPR regulations and agree to the terms of use and privacy policy.

Featured

Virtus KAR Small-Mid Cap Growth Fund Q2 2026 Commentary

August 16, 2026

Are we entering a post-Keynesian interregnum?

July 11, 2026

Europe’s Cross-Border Conundrum: The Battle for Sovereignty and Blockchain Dominance

June 11, 2026
Monthly Featured

Nearly three in four Indian crypto investors are under 35: CoinSwitch study | Cryptocurrency

August 21, 2026

Iran experiencing ‘worst conditions’ of economic warfare: President Pezeshkian

August 26, 2026

3 Altcoins For Your Watchlist Before The Next Bull Run – InteractiveCrypto

May 7, 2026
Latest Posts

Baillie Gifford Opens Tokenised Bond Fund in Four Markets

September 30, 2026

Hedge fund Point72 hired the former head of JPMorgan’s equities central risk book

September 30, 2026

Should You Buy Solana or Bitcoin With $1,000?

September 30, 2026
SUBSCRIBE TO OUR NEWSLETTER

Get our latest downloads and information first. Complete the form below to subscribe to our weekly newsletter.


I consent to being contacted via telephone and/or email and I consent to my data being stored in accordance with European GDPR regulations and agree to the terms of use and privacy policy.

© 2026 Aspire Market Guides.
  • Contact us
  • Privacy Policy
  • Terms and Conditions

Type above and press Enter to search. Press Esc to cancel.

SUBSCRIBE TO OUR NEWSLETTER

Get our latest downloads and information first.

Complete the form below to subscribe to our weekly newsletter.


I consent to being contacted via telephone and/or email and I consent to my data being stored in accordance with European GDPR regulations and agree to the terms of use and privacy policy.