
The short answer: no for personal use, yes for a business or DAO. If you’re asking “can I open a bank account for my cryptocurrency” as an individual, you cannot open a personal crypto bank account. For a startup, Web3 company, or DAO, you can open a business account that combines fiat rails and USDC custody on one platform. The DOJ’s seizure of Tether bank accounts on September 25, 2026, makes the distinction urgent: how your account is structured and where custody sits determines whether authorities can freeze funds. Knowing the difference between an exchange account, a licensed crypto bank, and a neobank that provides partner-bank accounts is essential.
Table of Contents
The Three Account Types People Confuse
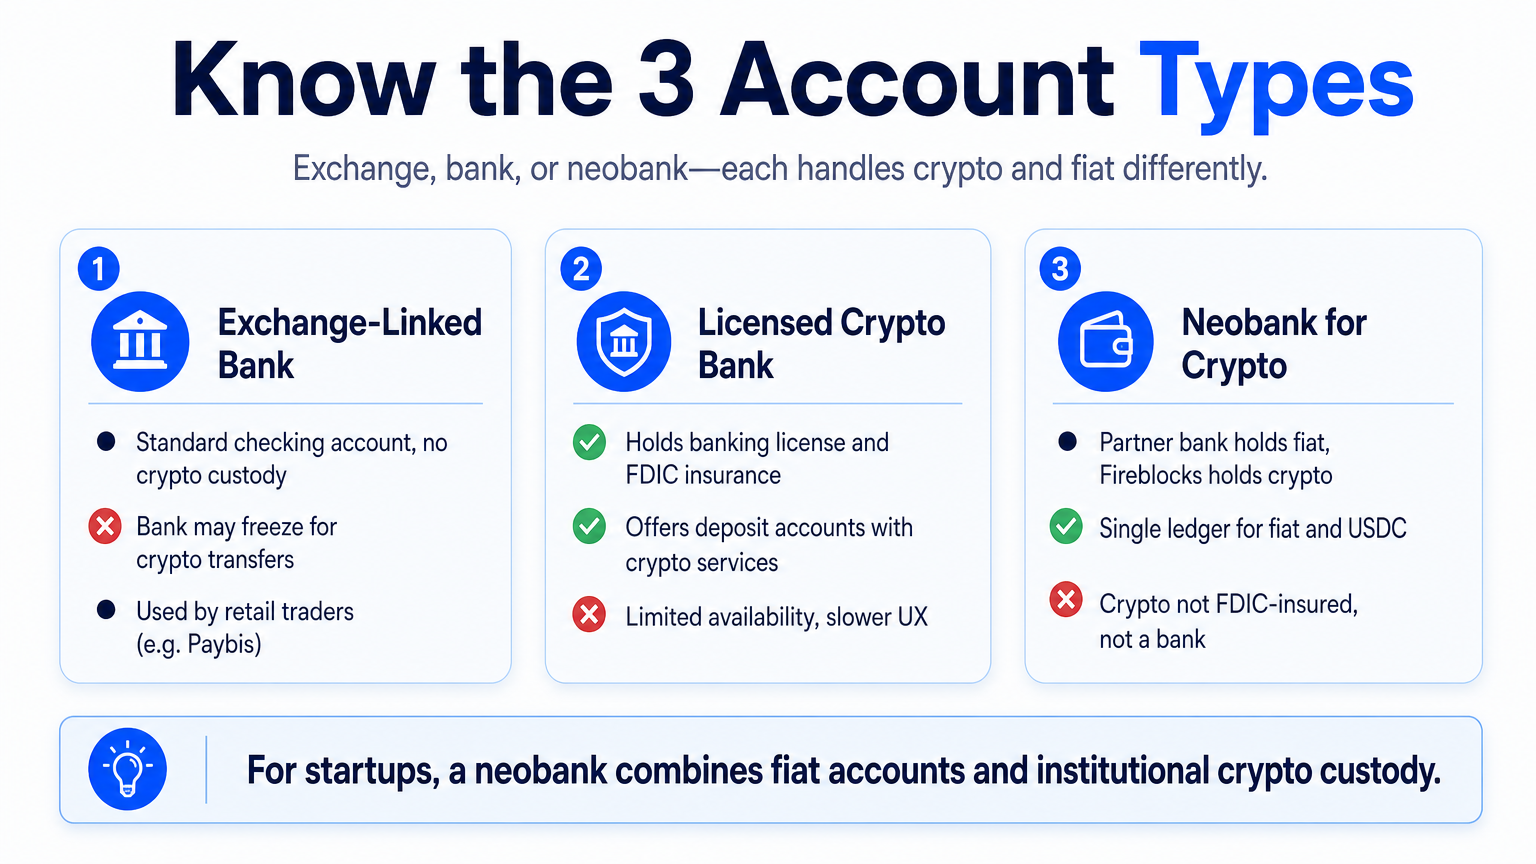
When you search for a crypto-friendly bank account or want to open bank account for crypto, you actually mean one of three different products.
Existing Bank Account Linked to an Exchange
Keep a standard checking account, link it to an exchange, and move dollars to trade. The bank holds no crypto and may freeze the account if it detects repeated exchange transfers—a risk since the Tether seizure. This is the Paybis/retail-user model.
Licensed Crypto-Friendly Bank with Dedicated USD Accounts
A few institutions (e.g. FV Bank) hold a banking license and offer deposit accounts with integrated crypto services. Funds may be FDIC-insured (up to $250,000). This is what a crypto bank actually is, but availability is limited and user experience often trails fintechs.
Neobank or Fintech with Partner-Bank Accounts and Crypto On/Off-Ramp
This is the neobank for crypto startups—OneSafe and Mercury (which does not custody crypto) fall here. The fintech provides the interface and compliance layer; a partner bank holds fiat deposits and provides routing numbers. Crypto sits in institutional custody (Fireblocks), not in a bank deposit account. You get a single ledger for fiat and USDC—a USDC bank account-like setup for your operating treasury. The trade-off: crypto is not FDIC-insured, and the fintech is not a bank.
Step-by-Step: Opening a Business Account with Fiat and Crypto
Eligibility and Documents
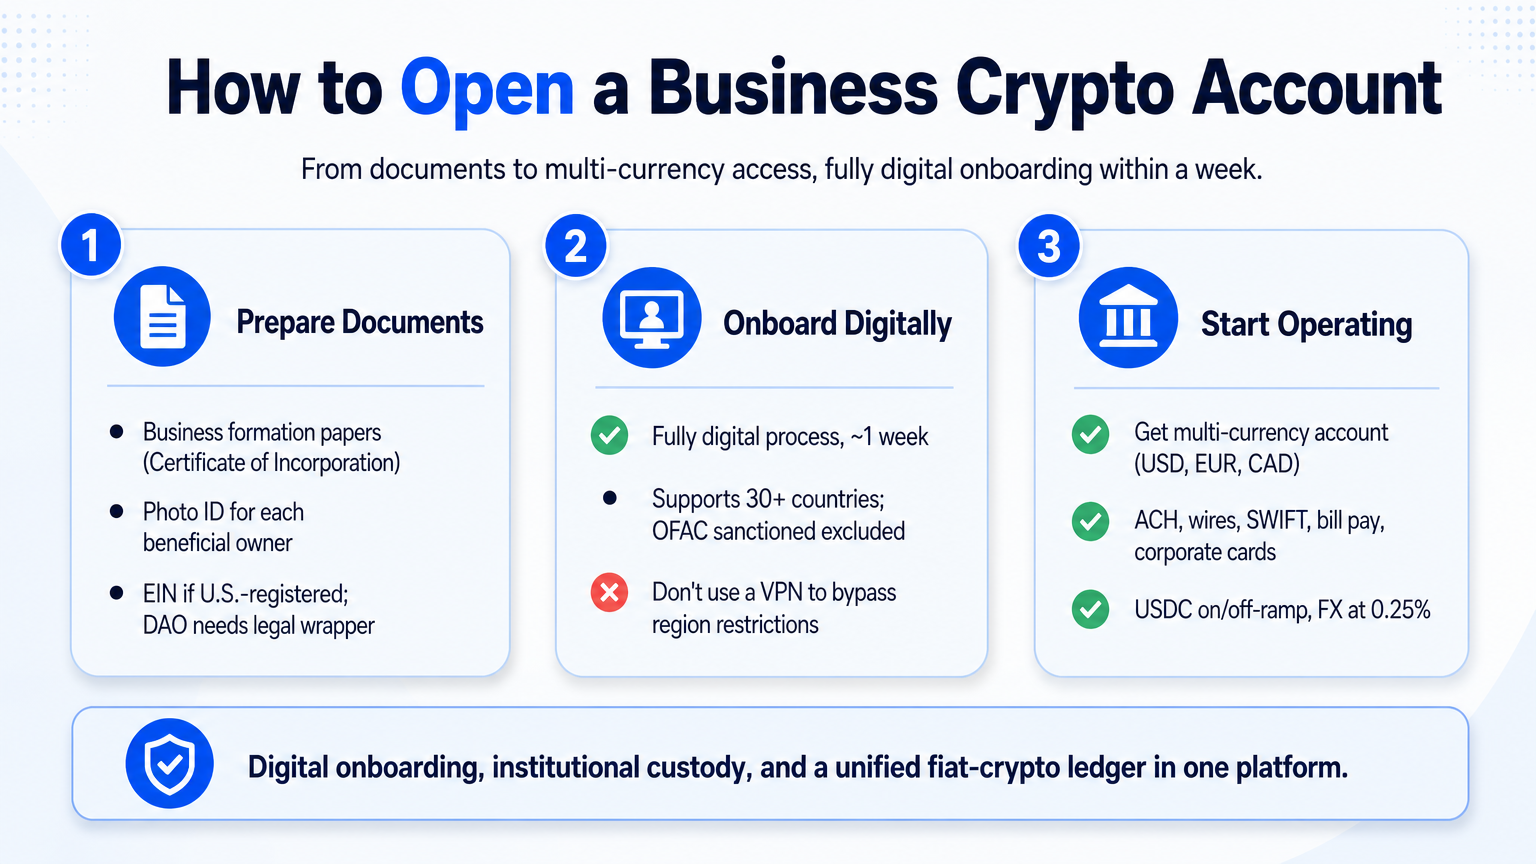
- Business formation papers (Certificate of Incorporation, Articles of Organization, etc.)
- Government-issued photo ID for each beneficial owner
- EIN if U.S.-registered. A DAO needs a legal wrapper (foundation or LLC) to pass KYB.
Onboarding and Availability
Fully digital onboarding typically completes within a week. OneSafe supports 30+ countries but excludes OFAC-sanctioned jurisdictions and certain U.S. states. Email support@onesafe.io for your state’s status. Do not use a VPN to bypass region restrictions; it will fail compliance.
After Approval
You get a multi-currency account (USD, EUR, CAD), ACH and domestic wires, SWIFT, bill pay, corporate cards (virtual cards free), and a USDC on/off-ramp. FX conversion is at 0.25%. Integrate accounting and automate payments.
Fees: What Actually Costs Money
| Transaction | Fee |
|---|---|
| Fiat deposit / withdrawal | 0.15% |
| Domestic wire withdrawal | $25 |
| Domestic wire deposit | $10 |
| SWIFT deposit / withdrawal | 0.35% + $50 |
| USDC deposit | Free |
| USDC withdrawal | Free |
| FX conversion | 0.25% or prevailing rate |
| Corporate card foreign transaction | 3% |
| Monthly account fee | $0 (free plan) or $29+ (premium) |
| Minimum balance | $0–$10,000 (varies by plan) |
The free tier lets you open a business bank account with no minimum balance and test the platform. Free USDC deposits/withdrawals are the largest cost advantage over exchanges that charge a percentage on every conversion.
Security, Custody, and What Partner-Bank Actually Means
OneSafe is a financial technology company, not a bank. Banking services are provided by partners. Digital assets are in Fireblocks institutional custody, and MFA is mandatory. Fiat balances held in the partner bank may be eligible for FDIC insurance up to $250,000. Crypto balances are not FDIC-insured—no neobank or exchange can insure digital assets.
If Your Bank Account Linked to Crypto Is Frozen
The Tether seizures show accounts can be frozen. Steps:
- Do not attempt to open another account at the same institution.
- Ask compliance for the specific reason in writing.
- Gather all transaction records, counterparty wallets, and invoices explaining the business purpose.
- A platform with segregated fiat and crypto custody gives you a cleaner trail—this is why a Web3-native account matters.
- If unresolved after 30 days, consult a crypto asset forfeiture lawyer.
Stablecoin regulation is evolving fast—ESMA’s MiCA demands and the Fed’s rules are tightening compliance scrutiny.
Troubleshooting Common Bank-to-Crypto Problems
- Transfer rejected or delayed: Usually a compliance flag. Check if the receiving platform serves your jurisdiction, if the amount fits expected cash flow, and if KYB is complete.
- Region error during signup: OneSafe excludes OFAC-sanctioned countries and some U.S. states. Email support; do not use a VPN.
- USDC deposit not in fiat balance: You must initiate the off-ramp conversion manually. If the deposit doesn’t appear, verify the network (ERC-20) and check Etherscan before contacting support.
- Wire withdrawal stuck or overcharged: Can be caused by incorrect beneficiary details, intermediary bank holds, or compliance review. SWIFT costs 0.35% + $50; request a GPI trace from the sending bank to locate it.
Answers to Specific Questions
Can I open a personal bank account that holds cryptocurrency?
No. OneSafe does not offer consumer accounts. Most licensed banks do not hold crypto as deposits. Consumer options: a crypto exchange account linked to a checking account, or a brokerage account like Fidelity Crypto. Compare actual banks that support Bitcoin.
What is the difference between a crypto exchange account and a crypto-friendly bank account?
An exchange account (Coinbase, Kraken) is a trading relationship holding assets in a pooled wallet. A crypto-friendly bank account (licensed bank or neobank) gives a dedicated business account with unique routing numbers for fiat, plus separate crypto custody. You can pay vendors and send wires directly—an exchange cannot. See the guide to US banks supporting Bitcoin and stablecoins in 2026.
Can a business open an account that supports both fiat and crypto?
Yes. A business crypto account at a neobank provides partner-bank fiat accounts and USDC custody in one dashboard. OneSafe offers ACH, wires, bill pay, cards, and USDC on/off-ramp—a functional USDC bank account for operations. The Coinbase Business platform handles payments and custody but cannot replace a bank account for wires and bills.
What documents do I need to open a crypto business account?
Business formation papers, government-issued photo ID for each beneficial owner, and an EIN (if U.S.). KYB is mandatory. A DAO without a legal entity must form one before applying.
Are funds in a crypto-friendly account FDIC insured?
Fiat balances in partner-bank accounts may be insured up to $250,000. Crypto balances are never FDIC-insured. If insurance matters to your treasury policy, keep operating cash in fiat.
Which US states and countries are supported?
30-plus countries, excluding OFAC-sanctioned jurisdictions and certain U.S. states. Email support@onesafe.io with your jurisdiction before onboarding.
Can a DAO open an account with role-based permissions?
Yes, you can open account for DAO by forming a legal entity that passes KYB. OneSafe then allows customizable roles and permissions to match your governance. The fiat account belongs to the legal entity; crypto remains in Fireblocks custody with mandatory MFA, bridging on-chain governance and off-chain banking.
What are the fees for wires, FX, and crypto deposits/withdrawals?
See the fee table above. Most surprising: SWIFT costs 0.35% + $50, and corporate card FX carries a 3% fee. USDC deposits and withdrawals are free. Plan treasury flow around the 0.15% fiat fee and $25 wire cost to minimize expenses.
Key Takeaways
- No personal bank account holds crypto directly. For businesses, the practical answer is a neobank with partner-bank fiat accounts and institutional crypto custody.
- USDC deposits and withdrawals are free, but fiat wires and FX carry costs. Design your treasury around the fee structure.
- A frozen bank account after crypto transfers is a compliance issue—segregate fiat and crypto custody and keep clean records, especially after the Tether seizure.
- DAOs need a legal wrapper to open a fiat account; once verified, role-based permissions give treasury teams full control.
Start your application at onesafe.io for a business account that handles fiat, USDC, and multi-currency operations from a single platform.