
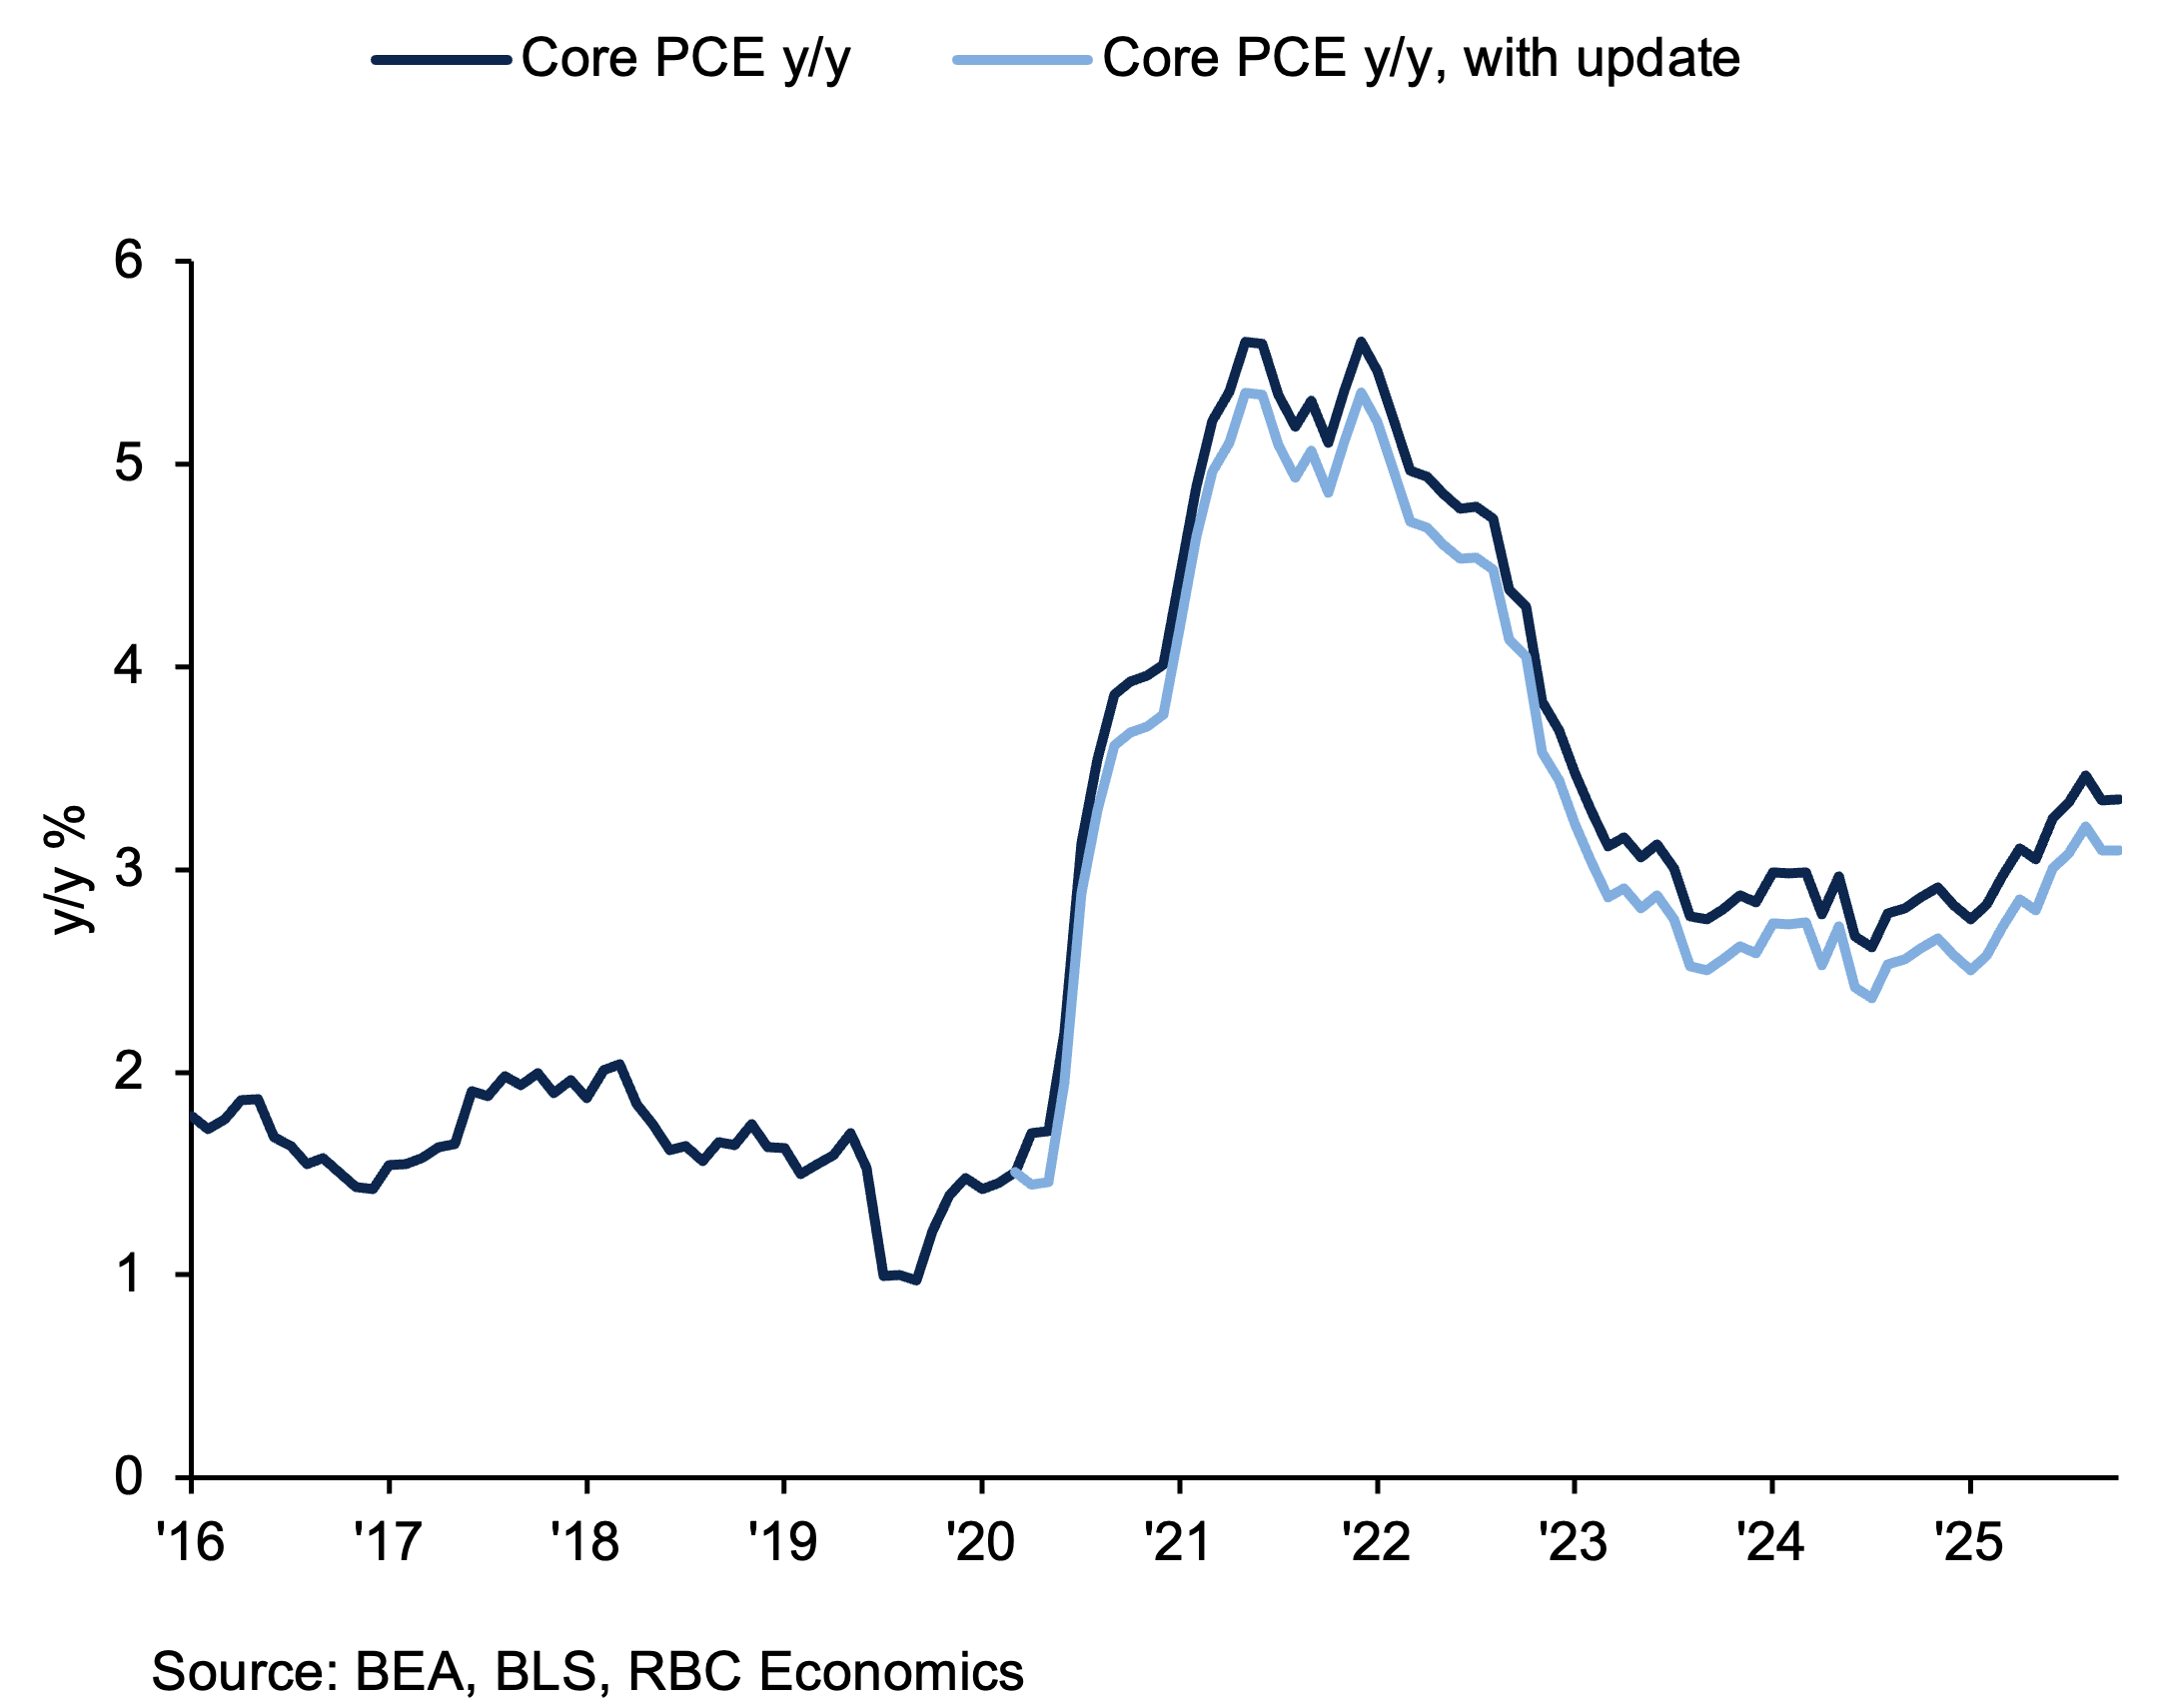
Updates to the Personal Consumption Expenditures (PCE) deflator methodology set to be released this month will be a one-time shift in measured inflation in the US—which we think will lead to a lower-than-expected reading—but that shouldn’t alter the underlying trend.
The Bureau of Economic Analysis (BEA) announced updates to the PCE deflator methodology to be released on Sept, 30, 2026. The changes will be applied retroactively through Q1 2021, and be used in the estimation of monthly PCE deflators going forward.
We anticipate an 18-basis-point reduction in the annual pace of core PCE as a result—meaning core PCE in July would be revised down to 3.1% from 3.3%.
Importantly, we caution against misinterpreting a lower-than-expected reading on Wednesday as a sign of disinflation ahead.
Three changes are being made to the methodology:
-
Portfolio management and investment advice services: Nominal price deflation is being replaced entirely by a Current Employment Statistics (CES)-based quantity series.
-
Computer software and accessories: Nominal price deflation is being maintained, but with a new deflator—a composite index of various Producer Price Indexes (PPI) and Consumer Price Indexes (CPI), rather than CPI for computer software and accessories alone.
-
Legal services: Nominal price deflation is being maintained with a new deflator. The current CPI deflator has proven unreliable and been suppressed.
We discuss each change, and assess the respective impact on PCE’s measured pace of inflation.
Portfolio management and investment advice services
We expect portfolio management and investment advice services to contribute less to PCE inflation following the update.
The BEA has not yet shared full details on the new quantity estimation approach. However, we suspect the quantity estimate will be based on average weekly hours growth for the sector. The Bureau of Labor Statistics (BLS) CES program publishes hours worked and employment alongside average hourly earnings. Since the BEA specifically describes a “quantity extrapolator,” hours growth would be a more intuitive quantity measure than average hourly earnings, which is a price measure of labor.
Under the current methodology, nominal spending is deflated to real spending using the PPI series for portfolio management and investment advice services.
The new methodology replaces the PPI series with a derived price index, obtained through the relationship between nominal and real spending—where real spending is implied by the new quantity extrapolator (i.e., hours worked and aggregate earnings).
Since November 2025, portfolio management has contributed an average of 0.28 percentage point to the annual rate of core PCE inflation. Based on our assessment, at a weight of 1.7% of core PCE, the old deflator averaged 14.1% year-over-year since December 2023, while the new implied price index (assuming it reflects nominal PCE for portfolio management adjusted by aggregate hours and earnings for the corresponding NAICS code) averages 12.3%. The result is a decline in the contribution to core PCE of about 0.03 percentage point from 0.23 to 0.20 percentage point.
Computer software and accessories
The PCE price index for computer software and accessories has been significantly elevated since November 2025. The average contribution to headline PCE has run strong at 0.12 percentage point between November 2025 and July 2026, unusual for a segment that typically subtracted from inflation prior to 2025. This likely reflects recent demand surges for memory and computing products.
Mismeasurement arises because the PCE nominal spending category is deflated by the CPI for computer software and accessories. But the PCE spending category does not include all memory and storage products. Using the CPI series as a deflator, therefore, introduces measurement error.
Research from the Board of Governors of the Federal Reserve System identifies additional issues, including a lack of quality adjustments and pricing model shifts. Our reading of the BEA methodology note is the adjustments will address only the category mismatch. The Fed estimated the annualized contribution to core PCE would decline by about 0.16 percentage point (from 0.66 to 0.50 percentage point) following this correction.
Legal services
Legal services is the smallest contributor among the three components receiving adjustments with an importance weight of 0.76%. We expect the contribution to annual core inflation from this segment will increase modestly to 0.05 percentage point from an average of 0.04 percentage point since December 2023.
The main concern for this series is the consistency of the CPI data used for deflation. The BEA has resolved to use a composite price index of PPIs, but has not yet disclosed which specific series will be included.
PCE deflators update in September expected to shift core inflation slightly lower
About the authors:
Mike Reid is Head of US Economics at RBC. He is responsible for generating RBC’s US economic outlook, providing commentary on macro indicators, and producing written analysis around the economic backdrop.
Carrie Freestone is a Senior US Economist at RBC. She is responsible for generating RBC’s US economic forecasts across GDP, employment, and inflation, and providing macro commentary through publications, presentations, and the media.
Imri Haggin is an US Economist at RBC, where he focuses on thematic research. His prior work has centered on consumer credit dynamics and treasury modeling, with an emphasis on leveraging data to understand behavior.