
Close Menu
Aspire Market Guides
  • Home
  • Alternative Investments
  • Cryptocurrency
  • Economics
  • Equity Investments
  • Mutual Funds
  • Real Estate
  • Trading
What's Hot

Dangote Refinery IPO: Macroeconomic Impact, Investment Opportunities and Market Implications

September 13, 2026

Why Madonna had her vagina scanned to make the worst NFTs ever in 2022

September 13, 2026

Apollo Global Management (APO) Curbed Redemptions In Its Private Credit Fund

September 13, 2026
Facebook X (Twitter) Instagram
Trending:
  • Dangote Refinery IPO: Macroeconomic Impact, Investment Opportunities and Market Implications
  • Why Madonna had her vagina scanned to make the worst NFTs ever in 2022
  • Apollo Global Management (APO) Curbed Redemptions In Its Private Credit Fund
  • Dale Jackson: Looking for a cash haven from the trade war?
  • 5 top flexi-cap funds in September with over 15% CAGR; how they compare on SIP, volatility measures – upstox.com
  • Private markets and AI top asset manager priorities as scale becomes the real challenge
  • Bitcoin vs Ethereum ETFs: Which asset is winning September’s flow battle?
  • The European Institute to host Workshop on Behavioural Macroeconomics and Finance with the Bank of England
  • 750-ton excavator cab catches fire at Australian gold mine
  • Nubank’s Stablecoin Move Signals New Era for Crypto Banking
Sunday, September 13
Facebook X (Twitter) Instagram
Aspire Market Guides
  • Home
  • Alternative Investments
  • Cryptocurrency
  • Economics
  • Equity Investments
  • Mutual Funds
  • Real Estate
  • Trading
Aspire Market Guides
Home»Economics»ECONOMIC WEEK AHEAD: April 27-May 1
Economics

ECONOMIC WEEK AHEAD: April 27-May 1

By CharlotteApril 26, 20263 Mins Read
Share
Facebook Twitter Pinterest Email Copy Link


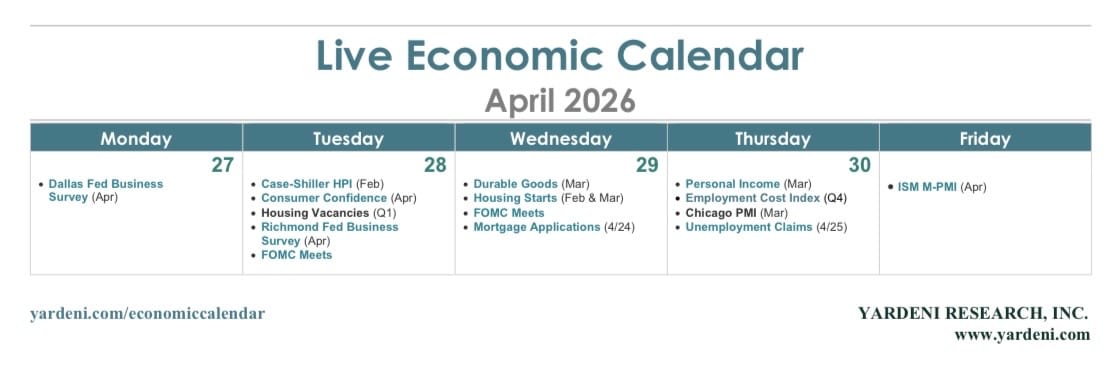
This is one of the busiest weeks of the year on the economic calendar. Five major central banks meet: the Fed, the Bank of Japan, the Bank of Canada, the European Central Bank, and the Bank of England. Five mega-cap tech names report earnings: Alphabet, Amazon, Meta, Microsoft, and Apple. Wednesday brings the advance Q1-2025 GDP report, and Thursday the March PCED, which will show how much of the oil shock has hit the Fed’s preferred inflation gauge. There will also be plenty of fresh survey data, with regional business surveys complementing Friday’s national M-PMI print, plus the Conference Board’s April Consumer Confidence Index, all on tape.

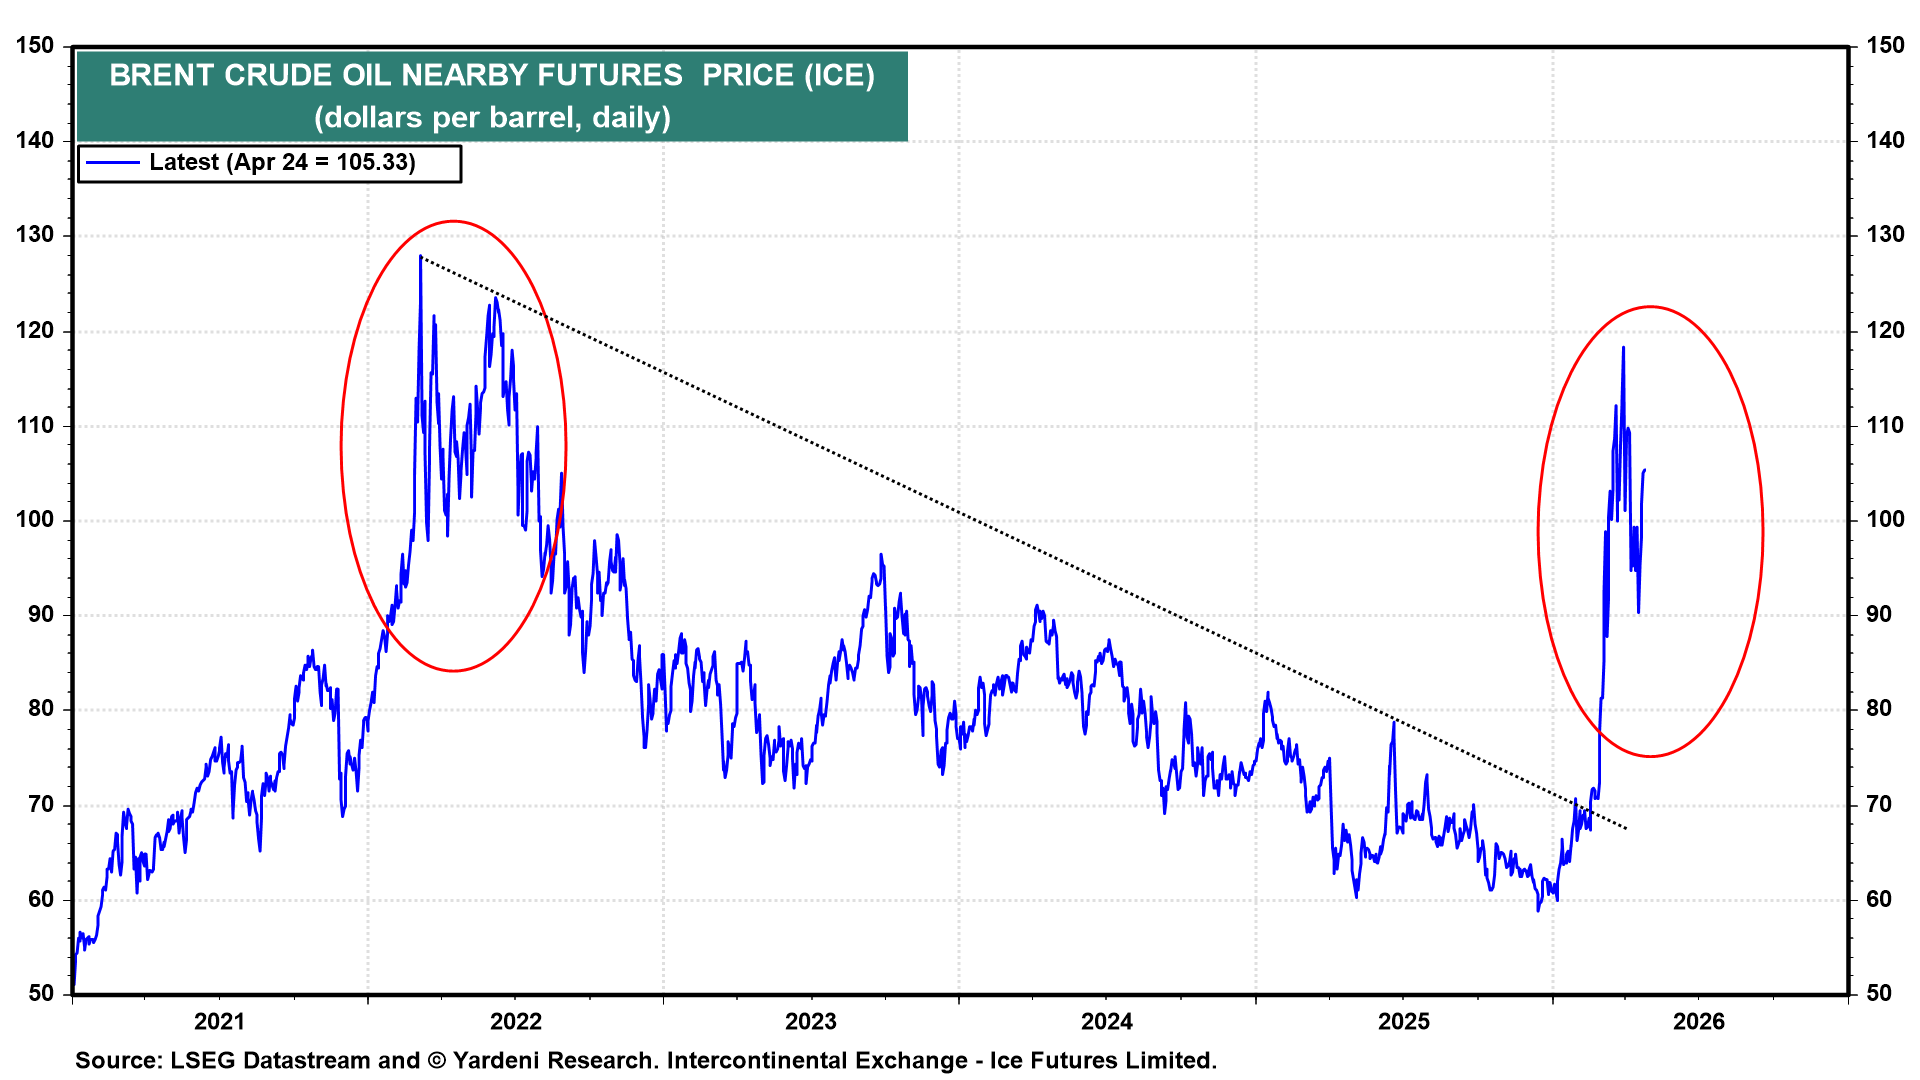
The blockade of the Strait of Hormuz by both the US and Iran remains the overriding issue. Both the US and Iran declined to meet in Islamabad this weekend. The price of a barrel of Brent crude closed at $105.33 on Friday, almost $20 above last week’s low (chart).
With that said, let’s take a look at the key releases most likely to shape investors’ thinking on growth, inflation, and the central bank reaction function this week:

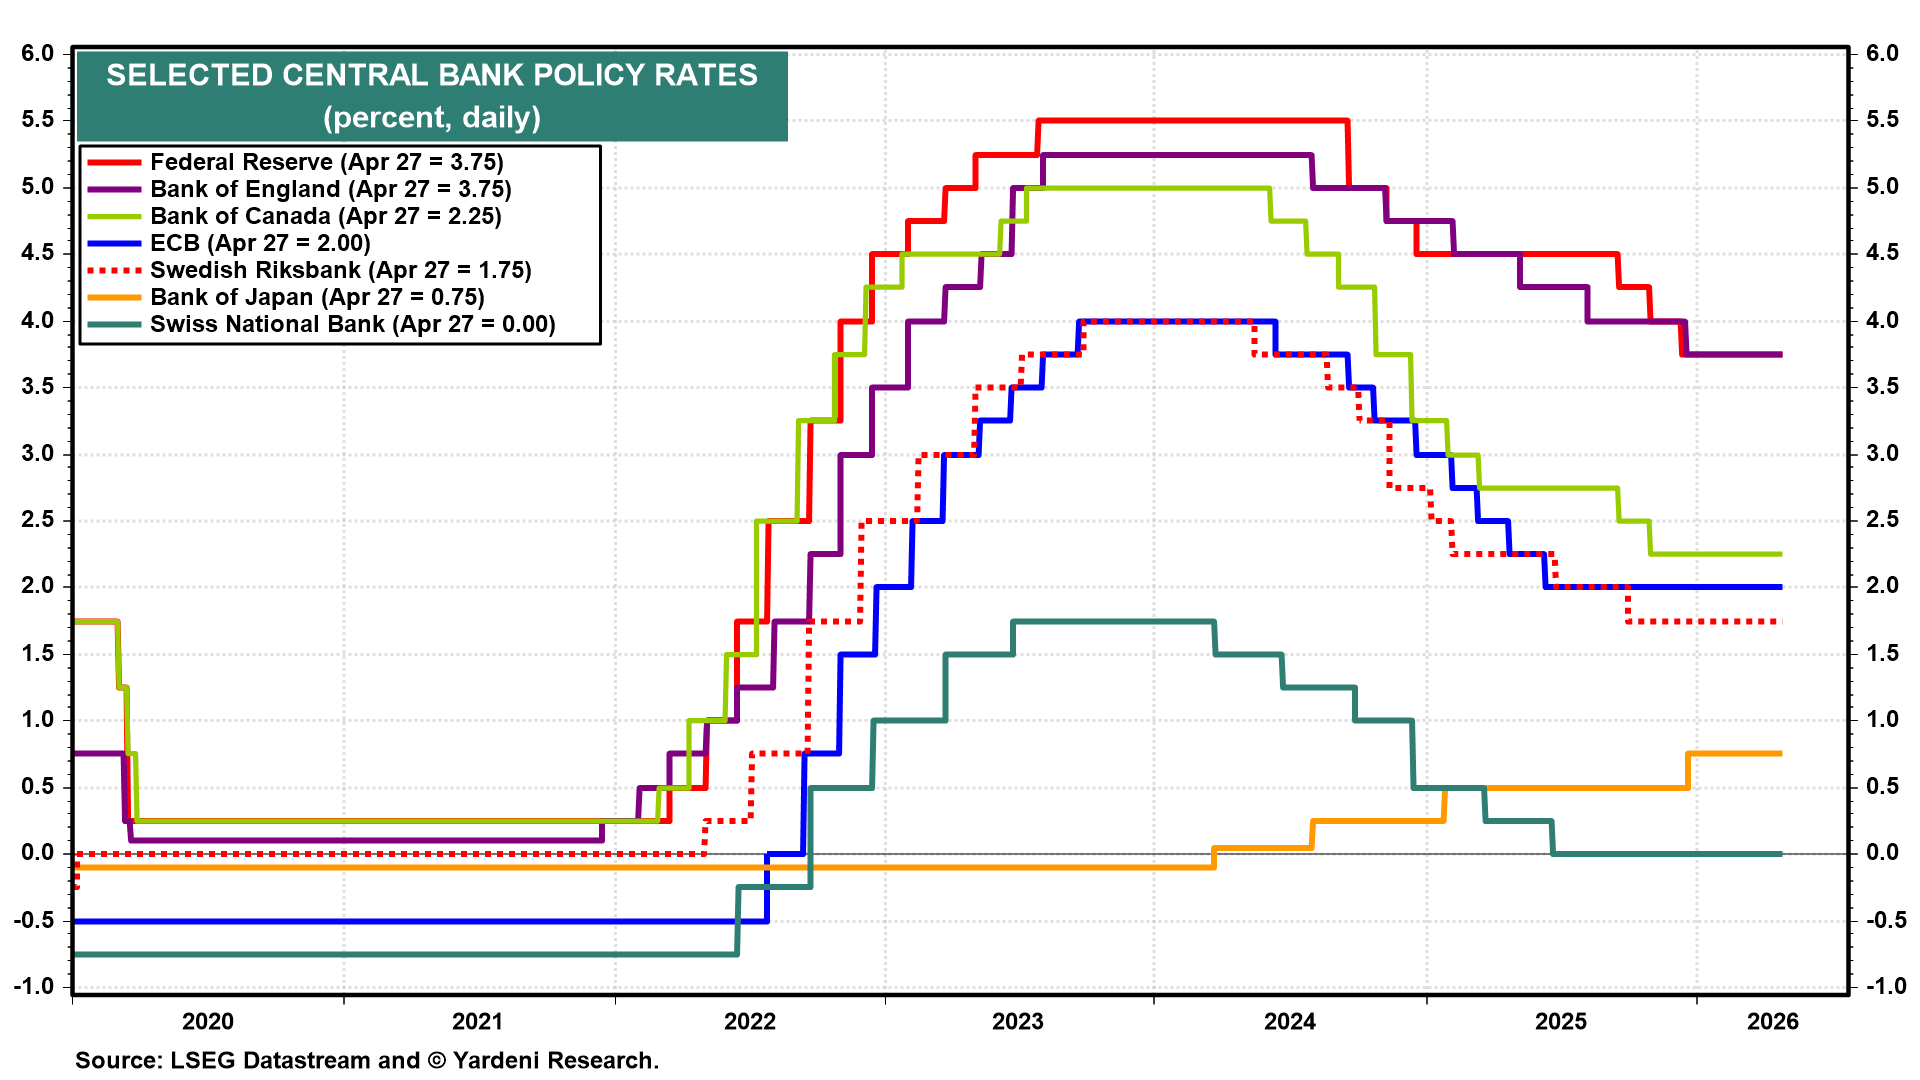
(1) FOMC and the global central bank docket. All five central banks are expected to remain on hold, leaving their policy rates roughly where they’ve been since late 2025 (chart). As is usually the case when the rate decisions themselves are foregone conclusions, investors will be reading the official commentary closely. Fed Chair Jerome Powell’s press conference on Wednesday is the main event. The pronouncements of the other central bankers all will be parsed for how they frame the oil shock, the growth slowdown, and inflation pass-through.
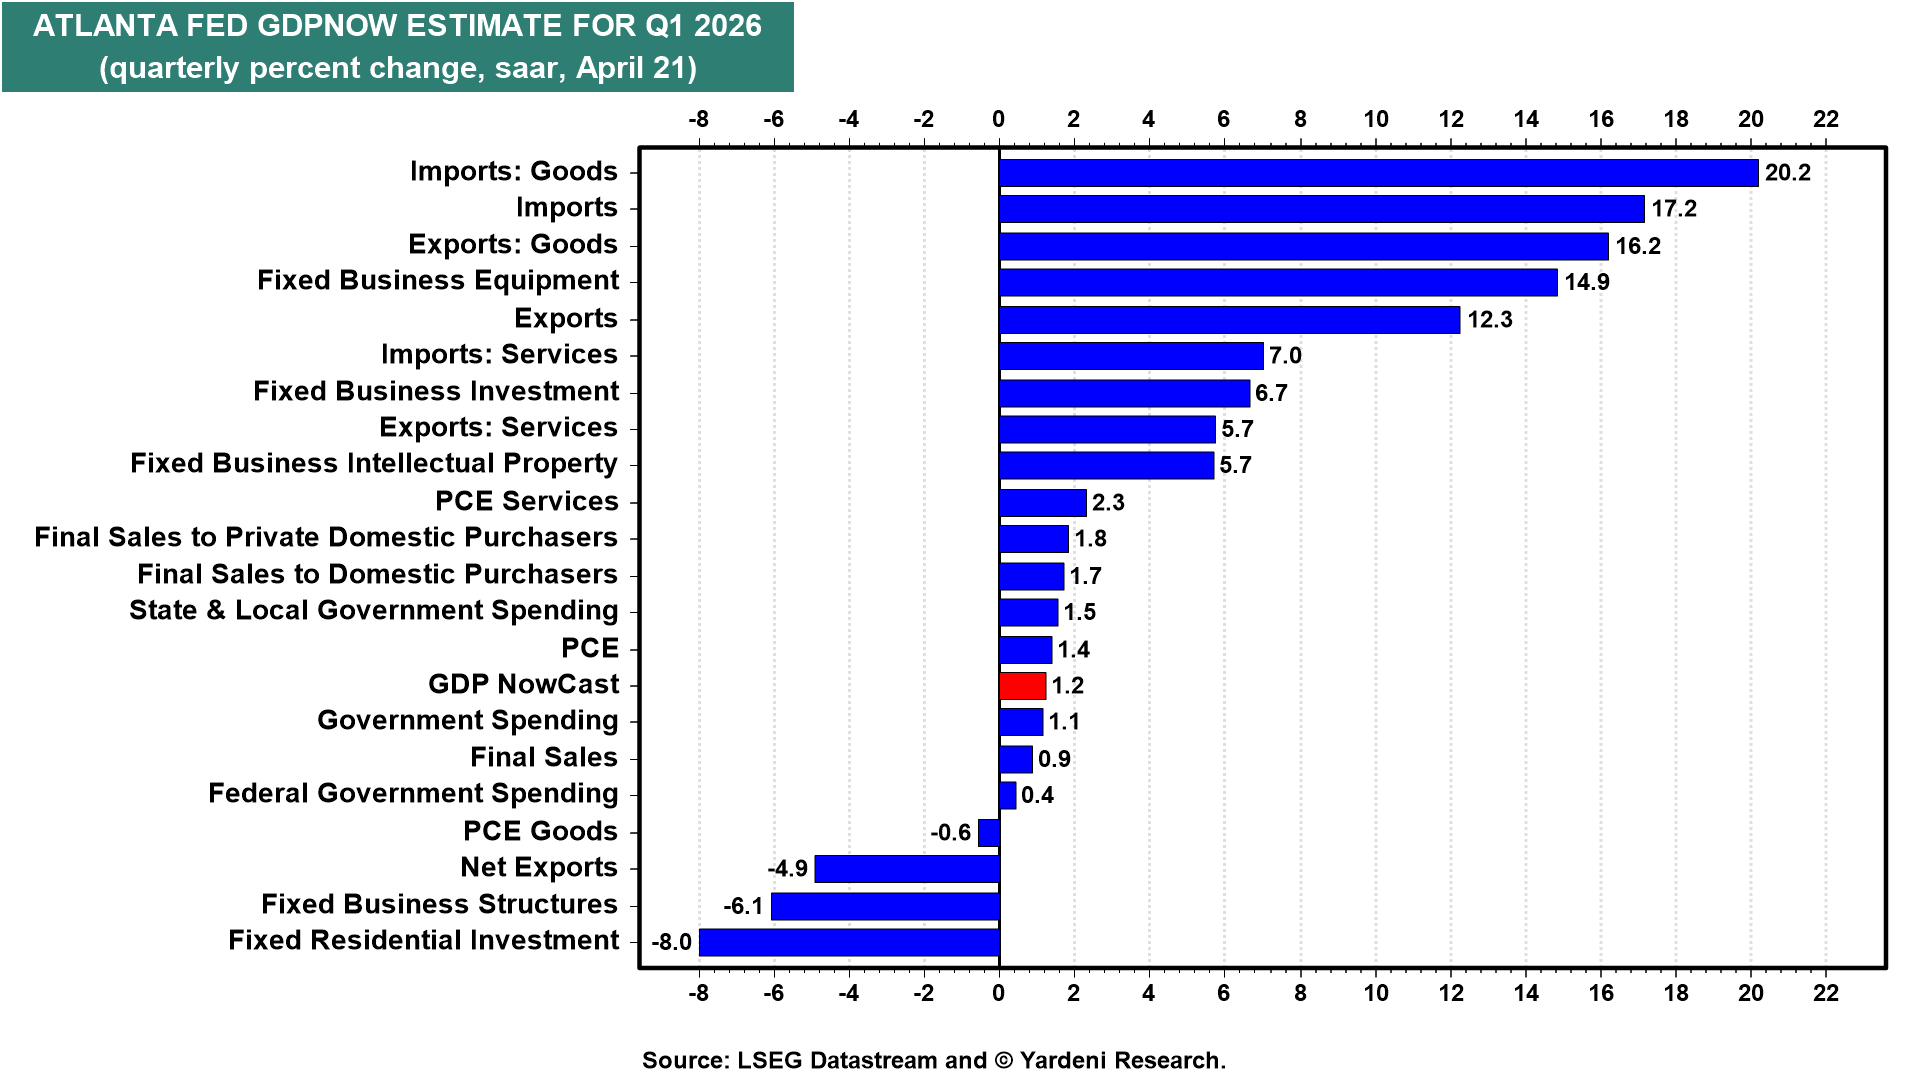
(2) GDP. Q1-2025 GDP (Wed) is likely to be up 1.2% according to the Atlanta Fed’s GDPNow model. We are still blaming bad weather in January and February for the weakness (chart).
(3) Inflation. March PCED (Thu) is the first clean read on how much of the oil shock is reaching the Fed’s preferred inflation gauge. Headline PCED inflation was 2.8% y/y in February (chart). The Cleveland Fed’s Inflation Nowcasting model projects headline inflation to rise to 3.39% y/y in March (0.59% m/m).
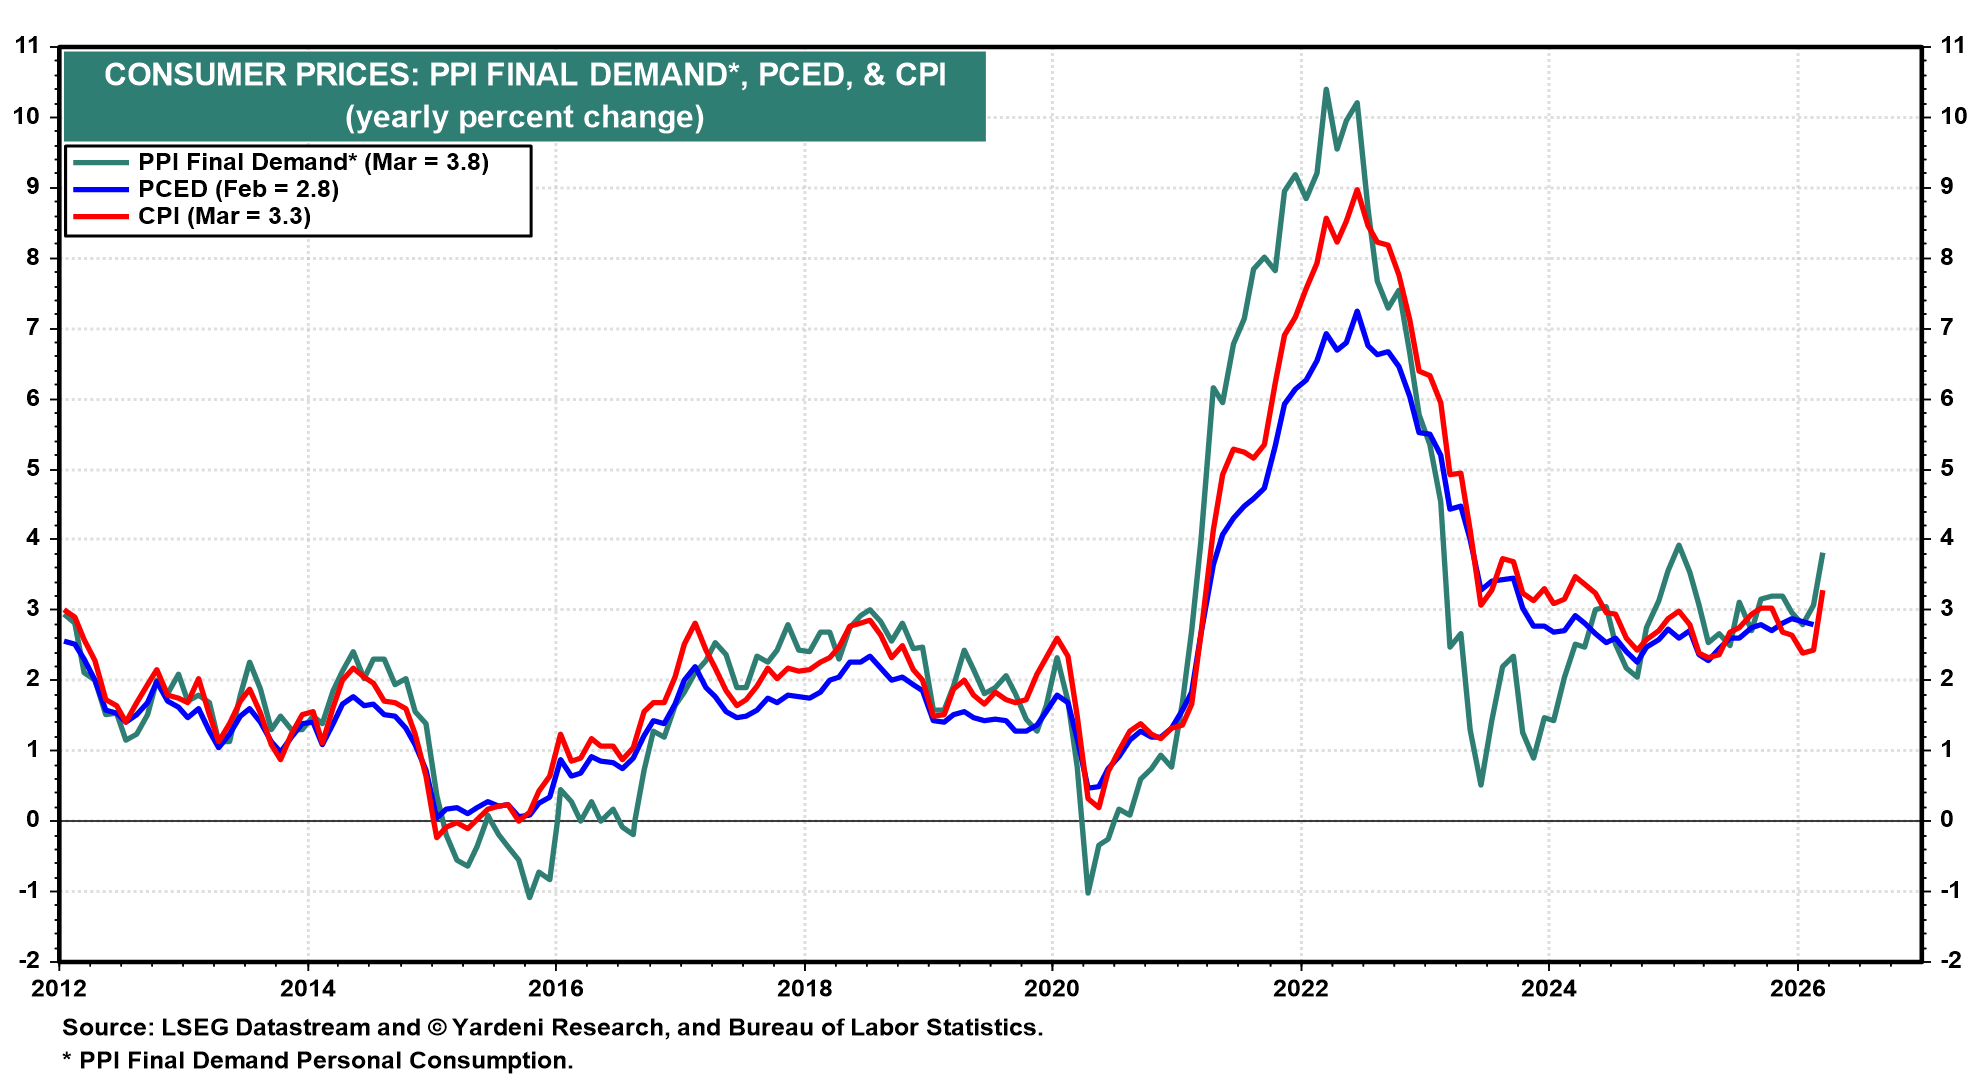
The core PCED inflation rate is tracking at 3.10% y/y and 0.23% m/m (chart).
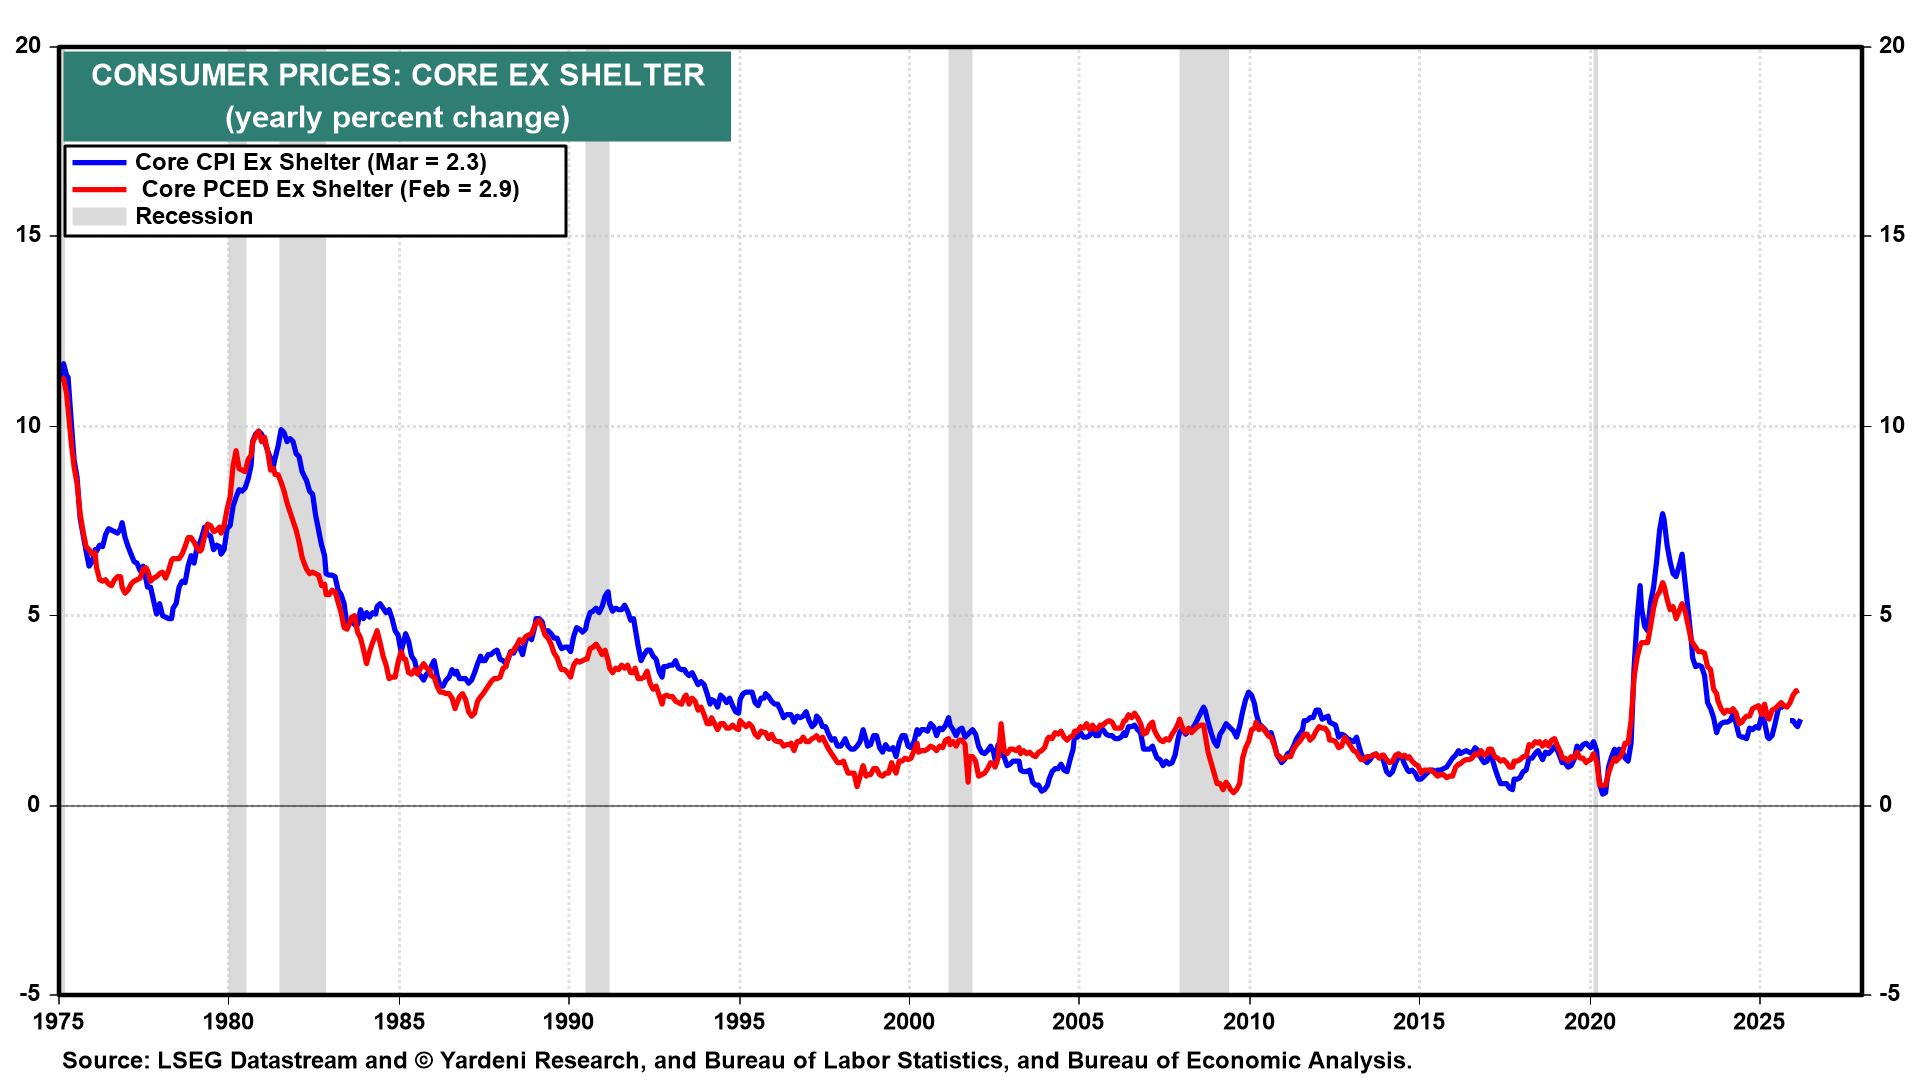
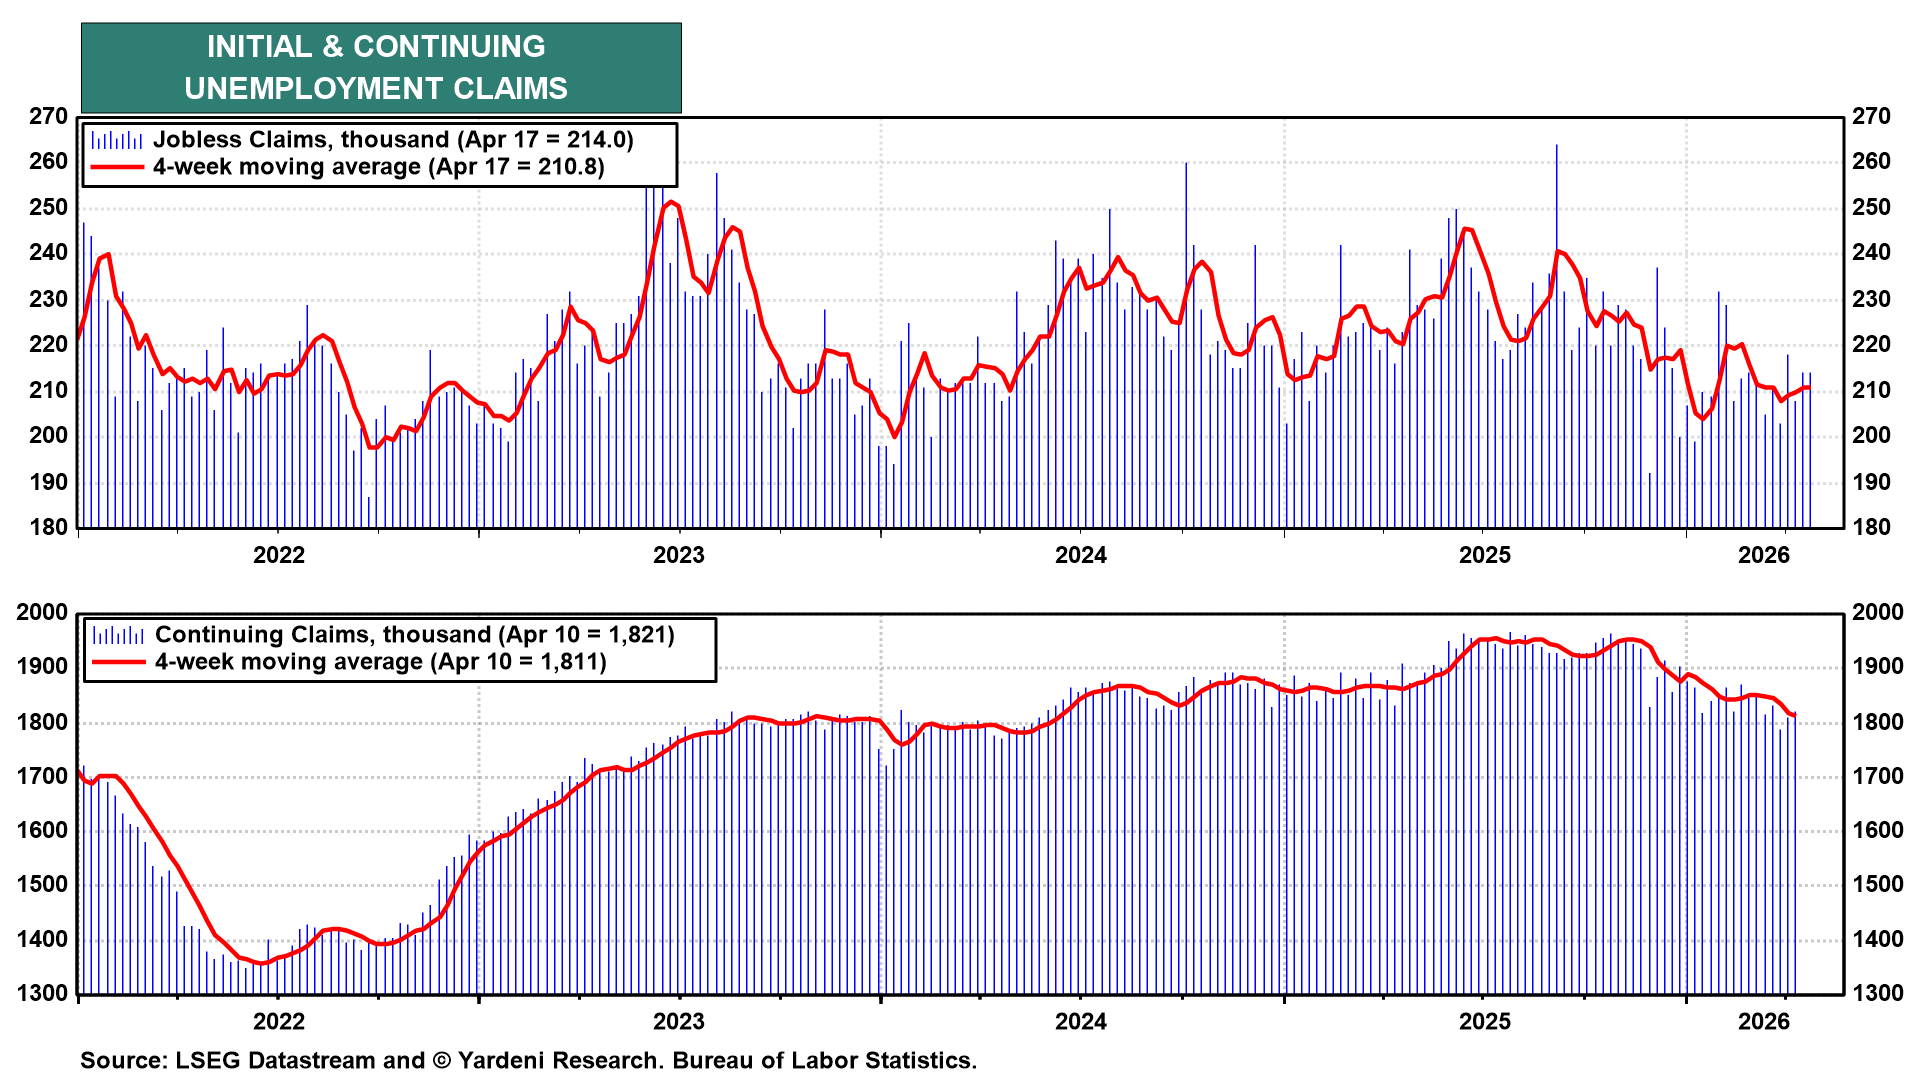
(4) Unemployment. Initial jobless claims (Thu) rose to 214,000 for the week of April 17, with the four-week moving average edging up to 210,800 (chart). Continuing claims ticked up to 1,821,000, though the four-week moving average continues to trend lower (chart). The labor market likely remained resilient during the second half of April.
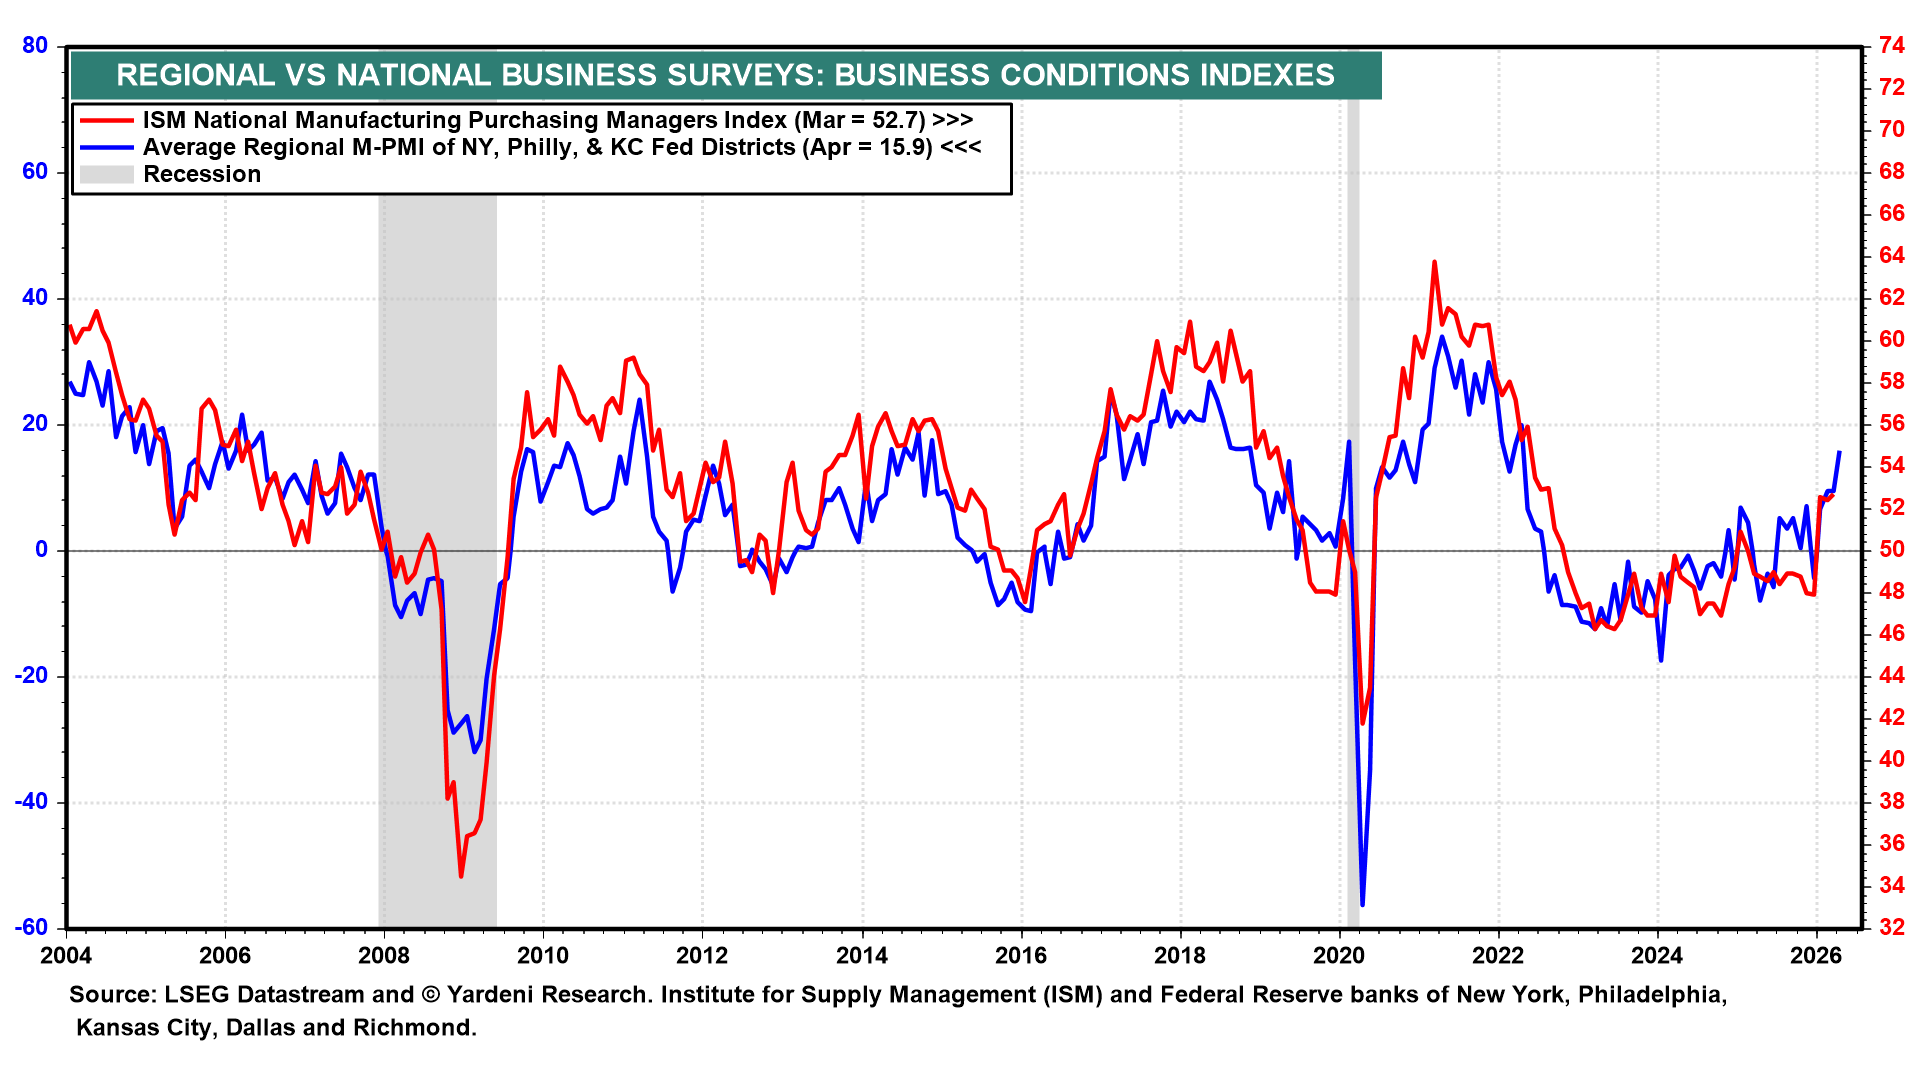
(5) Manufacturing surveys. Along with Friday’s national M-PMI, business surveys will be released by the Dallas Fed (Mon), Richmond Fed (Tue), and Chicago PMI (Thu). The April regional composite already sits at 15.9 based on the three available surveys (chart). That suggests another solid reading for April’s M-PMI.
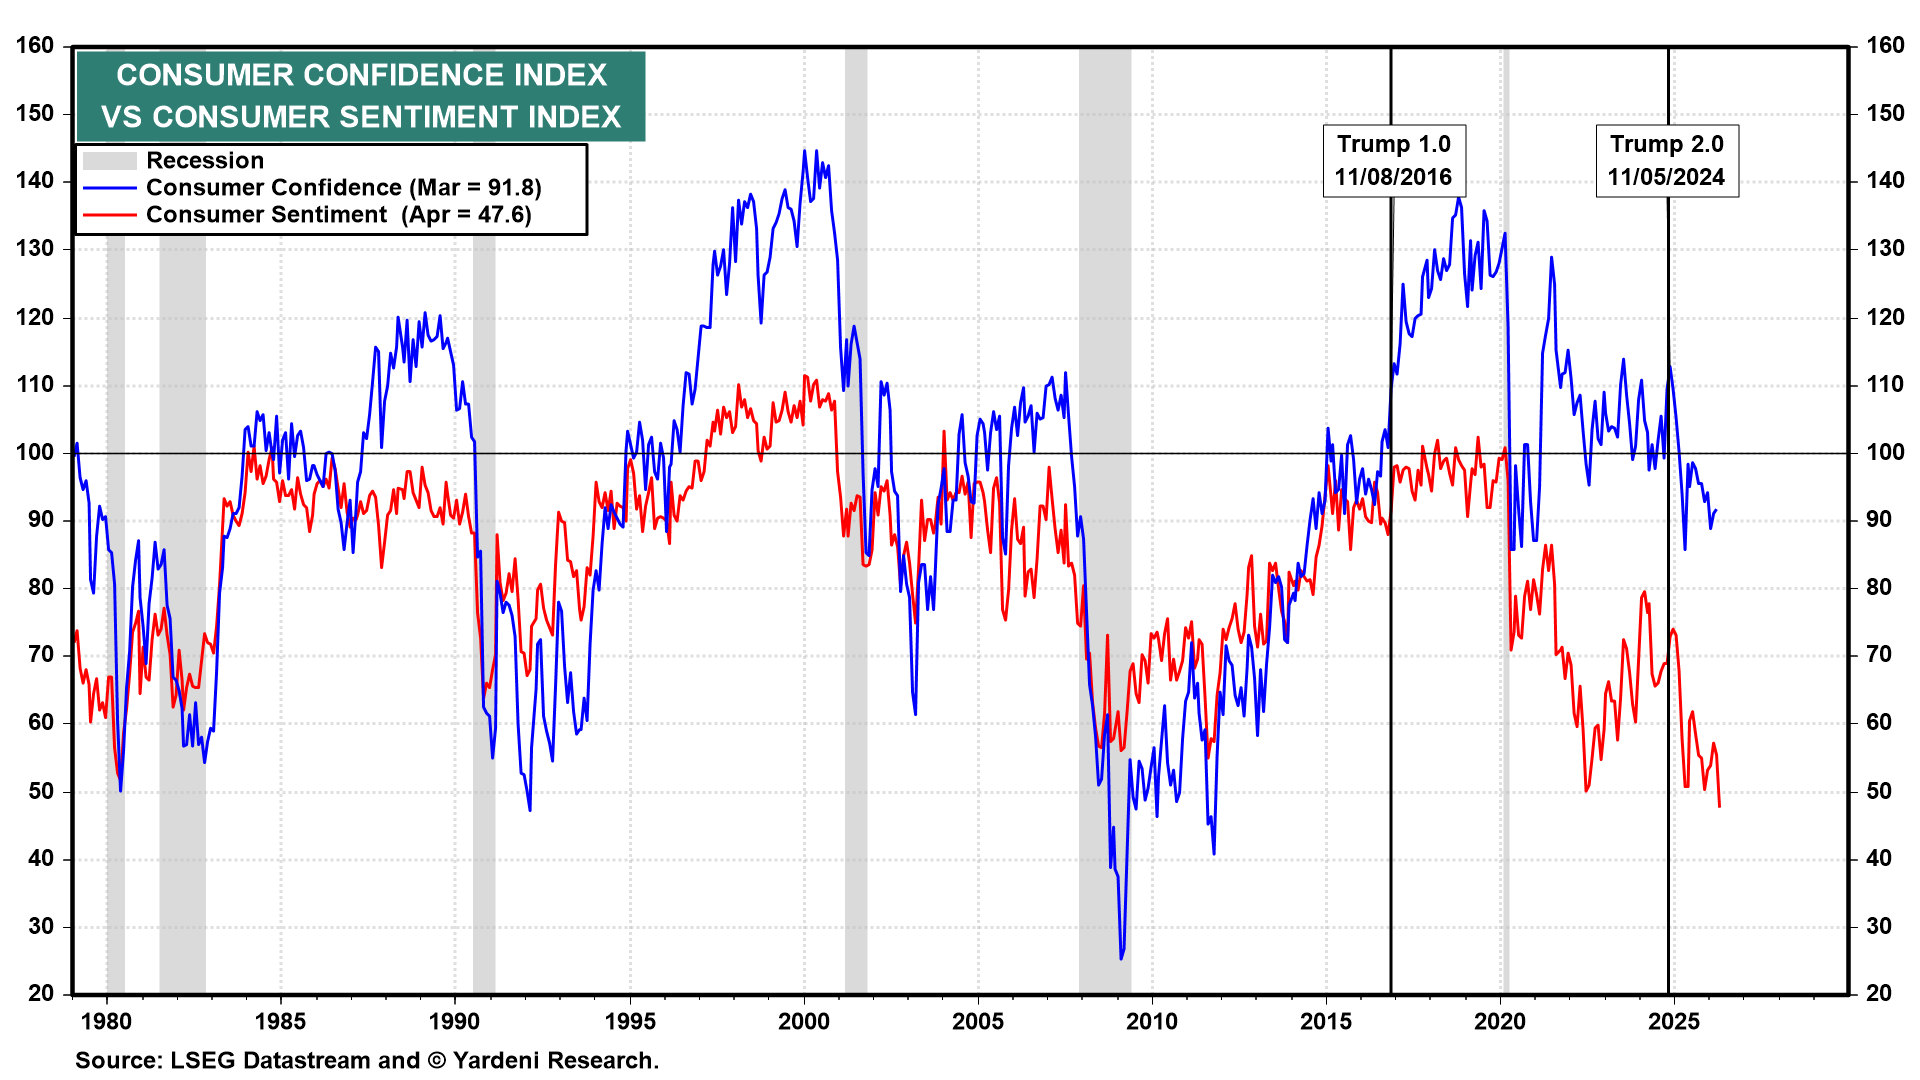
(6) Consumer Confidence. April’s Consumer Confidence Index survey (Tue) might follow April’s Consumer Sentiment Index lower (chart). While sentiment matters, consumers are still spending for now. The latest CCI survey might find that employment indicators are showing some signs of life, in our opinion.
💡

Join the discussion with Ed below! To leave comments or questions, log in to the Yardeni QuickTakes website and post them at the end of the QuickTakes article. Paid members’ contributions may be featured in our segment, “Ed Answers Your Questions”.


Source link

Related Posts

Economics

Dangote Refinery IPO: Macroeconomic Impact, Investment Opportunities and Market Implications

September 13, 2026
Economics

The European Institute to host Workshop on Behavioural Macroeconomics and Finance with the Bank of England

September 13, 2026
Economics

Macroeconomic Forecast – August 2026

September 13, 2026
Economics

The state of the Ukrainian economy is deteriorating rapidly across all key indicators

September 13, 2026
Economics

Austrian economic outlook improving – Business Recorder

September 12, 2026
Economics

LME aluminium prices weaken amid profit-taking, macroeconomic pressure

September 12, 2026
Add A Comment
Leave A Reply Cancel Reply

Editors Picks

Dangote Refinery IPO: Macroeconomic Impact, Investment Opportunities and Market Implications

September 13, 2026

Why Madonna had her vagina scanned to make the worst NFTs ever in 2022

September 13, 2026

Apollo Global Management (APO) Curbed Redemptions In Its Private Credit Fund

September 13, 2026

Dale Jackson: Looking for a cash haven from the trade war?

September 13, 2026
SUBSCRIBE TO OUR NEWSLETTER

Get our latest downloads and information first. Complete the form below to subscribe to our weekly newsletter.


I consent to being contacted via telephone and/or email and I consent to my data being stored in accordance with European GDPR regulations and agree to the terms of use and privacy policy.

Featured

May Day: TUC urges gov’t to turn economic stability into jobs and better living standards

May 1, 2026

Retail investors lose Rs 91,685 crore in equity F&O trading in FY26, losses down compared to FY25: Govt

August 12, 2026

THE ECONOMIC IMPACTS OF LOCAL AND CONVENTIONAL FOOD SALES | Journal of Agricultural and Applied Economics

July 5, 2026
Monthly Featured

KETSA launches Alternative Investment Fund to unlock new

June 28, 2026

Understanding Price Elasticity’s Impact on Supply and Demand

April 15, 2026

Hyperliquid Sees Sunday Trading Volume Surge As Traders Position Ahead Of Monday Open

June 29, 2026
Latest Posts

Dangote Refinery IPO: Macroeconomic Impact, Investment Opportunities and Market Implications

September 13, 2026

Why Madonna had her vagina scanned to make the worst NFTs ever in 2022

September 13, 2026

Apollo Global Management (APO) Curbed Redemptions In Its Private Credit Fund

September 13, 2026
SUBSCRIBE TO OUR NEWSLETTER

Get our latest downloads and information first. Complete the form below to subscribe to our weekly newsletter.


I consent to being contacted via telephone and/or email and I consent to my data being stored in accordance with European GDPR regulations and agree to the terms of use and privacy policy.

© 2026 Aspire Market Guides.
  • Contact us
  • Privacy Policy
  • Terms and Conditions

Type above and press Enter to search. Press Esc to cancel.

SUBSCRIBE TO OUR NEWSLETTER

Get our latest downloads and information first.

Complete the form below to subscribe to our weekly newsletter.


I consent to being contacted via telephone and/or email and I consent to my data being stored in accordance with European GDPR regulations and agree to the terms of use and privacy policy.