
Suffice it to say, there are plenty of positive things to be said about Poland’s post-communist trajectory. Within the past 5-10 years, it isn’t difficult to stumble across articles praising the Polish economy as an example of what would happen after abandonment of socialism for something that resembles a market economy. I’m sure you’ve seen the headlines about the $1 trillion GDP pole which Poland recently obtained, the ongoing +3.5 percent real GDP figures, and even posts and articles about Poland surpassing Germany in the future—including those from normally free market institutions like FEE.
It is similar to the current state of modern media, for what makes the headlines ignores a lot of inconvenient facts to project a specific narrative—Poland’s case is not exceptional. This isn’t to say that Poland hasn’t made good strides, but much of the narrative of being an “European Tiger” or surpassing core European economies is dubious.
Growing, but Not There Yet
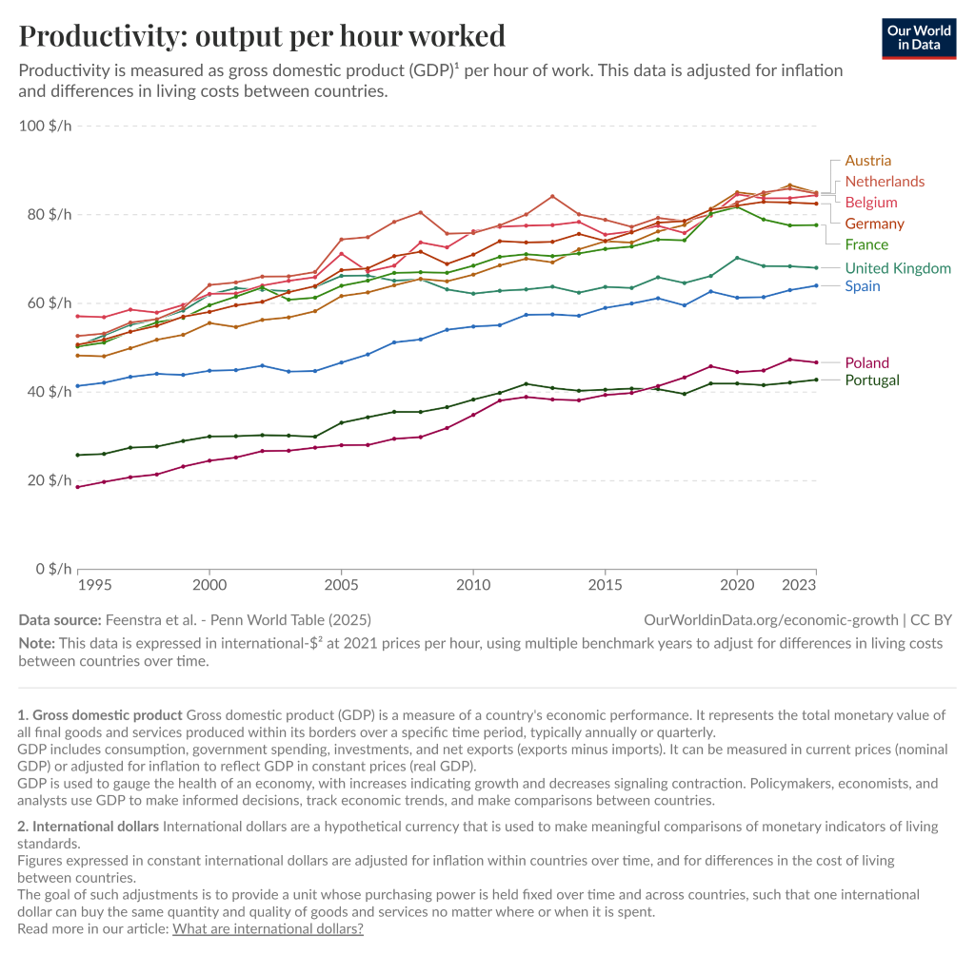
First of all, Polish GDP per capita remains within Portuguese levels and productivity levels remain half of most Western European countries. Convergence with and surpassing Western European countries remains improbable in the foreseeable future, because of real dependency issues with EU funding, on export-inflationary monetary regime, and a critically low (East Asian level) fertility rate.
This is because the Polish economy is based upon subcontracting and final assembly of Western (particularly German) consumer goods and automobiles—which, while of higher class than the Chinese and other non-East Asian economies, remains fundamentally dependent on repressing wage growth via inflation, subsidies, and preferential policies for rapid industrialization. This is confirmable via worker compensation remaining well-below productivity rates (though this has been the case for all economies since the end of the gold standard system) and historical trend to run higher inflation rates than Germany.
One of the predictable outcomes of this is simple: cost-of-living issues inhibiting replacement reproduction. While low fertility rates aren’t a uniquely Polish phenomenon, the acuteness of low Polish fertility rates are—as of 2025, Poland recorded a 1.1 TFR, which is far lower than most Western European levels between 1.3-1.6 and comparable to China, South Korea, Japan, and Taiwan. It doesn’t matter that only 4.6 percent of Poles pay 40 percent or more of their income towards rent compared to 11-13 percent in Western Europe, because should prices remain as elevated as they are or climb further, which is natural for an export-inflationary regime to maintain an artificial relative advantage of low labor costs. In other words, convergence is highly unlikely, because the Polish economy requires a structural cap on its people’s own earnings and savings to “achieve” growth.
Second of all, while Polish unemployment data reveals stronger performance compared to the average EU rate, and labor force participation rate is on par with EU average, the real problem emerges when you factor in over a million and a half Poles who left Poland to find work elsewhere in Western Europe. This is not a simple brain drain situation per se; many of the Poles didn’t migrate to metropolitan areas throughout Western Europe, but to depressed regions like Germany’s Uckermark (roughly around historically struggling Mecklenburg-West Pomerania and Brandenburg), Westphalia, and rural British areas, and they also work lower-end jobs like construction or elderly care. This is because the post-communist era, while did liquidate a lot of grotesque inefficient state entities like Polski Fiat (the communist-era automobile manufacturer), did not curb the strong legal powers of unions, the bureaucracy, and the liberalization was, at heart, a Keynesian project (which will be explained later).
A Poisoned Dependency
Third, and perhaps often unacknowledged is Polish dependency on EU funding. For those unaware, the EU has programs in which EU countries doing well or above average subsidize other less well off EU countries, such as in the form of Cohesion/Just Transition and Agricultural Funds. The criteria for receiving these funds are: I. has a GDP per capita below 75 percent or within the 75-100 percent range. II. willingness to adopt specified political reforms. Poland has long been the largest recipient of the funds, with a net total of 156 billion euros received ($180 billion) and is slated to receive an additional 76 billion euros ($87 billion). These funds are intended for infrastructure upgrades and agricultural support (cronyism, if you will).
The trouble lies in the fact that Germany has been for years, the biggest contributor to these funds, and Berlin has signaled that it wishes to conditionalize (or even limit) funding further. These are not cyclical developments, but politically structural ones—Germany itself is, as a whole, more inward-looking over its current troubles with immigration, recession, and massive existing subsidies for its own eastern states. In contrast, Poland continues to receive and often demands for more funding.
What truly makes the issue even more structural is the historical background to all of this. While people might have heard of Polish demands for 1.3 trillion euros in WWII-related reparations, another thing they might have never heard is the historical fact that most of Poland’s western and northern territories were part of Germany and majority German, not Polish. This is because after WWII, the Allies (chiefly the Soviets, Czechs, Poles, and Churchill himself) expelled over 12-14 million Germans from their homes in genocidal fashion (and can be classified as genocide). Polish rhetoric around the expulsions themselves have often been trivializing or outright offering justifications as “just punishment” for millions of innocent Germans, including the lynching and rape of elderly, women, and children, are naturally disgusting. The memory of the expulsions are reemerging within German discourse, which will fuel a lot more incentive to cut EU funding, especially when the traditionally Euroskeptic AfD is at an all-time popularity.
Why the Narrative Exists
On the one hand, no one should ever mourn socialism (there’s a reason why breadlines and gulags exist) and not too many would dismiss Poland as a pure artificial economic construct; Poland has, for all of its faults, achieved something concrete. The question that ought to be asked is how concrete the Polish economy and narrative are.
We typically have short memories and the vocabulary we use today is definitely different from yesterday. Recall when Ludwig von Mises scolded Fritz Machlup, Milton Friedman, etc. as “a bunch of socialists” for proposing fiat currency instead of the gold standard. Things are markedly different in today’s world, as Mises and Friedman are lumped into a singular “laissez-faire” category without understanding that fiat currency is just another tool for central planning, partial or total, and the fact that both men lived under the gold standard, with Mises being an ardent gold standard supporter, while Friedman was against it (especially post-Bretton Woods). There’s a reason why “capitalist” South Korea under Park Chung-hee and, later, Chun Doo-hwan ran massive inflation spikes and cycles and called their policies “Five-Year Plans,” yet modern historiography will always lazily apply the term “capitalist.”
There are plenty of history and reasons why leftists always label whatever they don’t like as “capitalism” or a consequence of and why they’re historically dishonest, but that’s for another day. The same can be said about Poland and repeated comparisons of the Polish economy to the historical West German social market economy (Soziale Marktwirtschaft) that triggered the German economic miracle, though the angle differs a bit. The Soziale Marktwirtschaft was, by all of today’s standards, an extremely free market liberalization that pegged the Deutsche Mark (the currency of the time) to gold via the US dollar (Bretton Woods system) and dismantled the Nazi central planning apparatus to create a vibrant and wealthy middle class and global heavyweights like Bosch, Siemens, and Volkswagen—the “Nazi people’s car” never took hold until the 1950s.
The difference is categorical: profitability is a signal of sustainability when the money is honest; people do not prematurely spend and invest because “they have it,” for they do not have the capacity, the savings to do so, and businesses back then sustained because they had to compete on merit to earn that capacity, something fiat currency is fundamentally not.
The low fertility rates, the dependencies, and the triumphant narrative mask a sad reality: the profit isn’t wholly real, the price of products are paid by the employees themselves, and thus, they simply choose not to invest in having children. Populist rhetoric, left or right, cannot explain these things without “warming” them up as a case of “profit over people/family” and enters a particular bind (at least in this case) of them asking for undoing what was made entirely for breadlines, or simply romanticize the narrative that ignores current troubles.
Poland, East Asia, and many other export-inflationary regimes face this particular bind, because as the world inflates whatever currencies, they too must respond with similar measures to keep artificial competitiveness at the expense of the very individuals, the population, who need the market undistorted.