
Close Menu
Aspire Market Guides
  • Home
  • Alternative Investments
  • Cryptocurrency
  • Economics
  • Equity Investments
  • Mutual Funds
  • Real Estate
  • Trading
What's Hot

NervGen to Restate Previously Filed Financial Statements Recognizing Non-Cash Accounting Adjustments

September 26, 2026

Macroeconomics Seminar with Gaston Navarro (Federal Reserve Bank Richmond)

September 26, 2026

CARNIVALORATION Q3 2026 Earnings Preview: Recent $CCL Insider Trading, Hedge Fund Activity, and More

September 26, 2026
Facebook X (Twitter) Instagram
Trending:
  • NervGen to Restate Previously Filed Financial Statements Recognizing Non-Cash Accounting Adjustments
  • Macroeconomics Seminar with Gaston Navarro (Federal Reserve Bank Richmond)
  • CARNIVALORATION Q3 2026 Earnings Preview: Recent $CCL Insider Trading, Hedge Fund Activity, and More
  • White Hat Operation Rescues 23K NFTs After Payment Processor Exploit | Social Hacking
  • MDP Acquiring Marygold Companies
  • South Korea tightens scalping rules as gray areas persist for spots and lines – CHOSUNBIZ – Chosunbiz
  • Deep Dive: Stablecoins and Adoption in 2026!
  • An open letter to the Governor of the Reserve Bank
  • We’ll try again and again… until we make it
  • $58 Million Multifamily Asset Sale Closed by Institutional Property Advisors in North Phoenix
Saturday, September 26
Facebook X (Twitter) Instagram
Aspire Market Guides
  • Home
  • Alternative Investments
  • Cryptocurrency
  • Economics
  • Equity Investments
  • Mutual Funds
  • Real Estate
  • Trading
Aspire Market Guides
Home»Equity Investments»Comment: Burnham’s plan for the NHS is uncertain
Equity Investments

Comment: Burnham’s plan for the NHS is uncertain

By CharlotteAugust 11, 20264 Mins Read
Share
Facebook Twitter Pinterest Email Copy Link


Zohaib Hashim, Manchester-based private equity lawyer and chief executive of Blackmont Legal, argues that a rush to reverse privatisation could be costly. 

Andy Burnham now has the top job in British politics. What he doesn’t have yet is a clear position on private equity in the NHS.

That ambiguity matters. Because whatever he decides next will land very differently from any decision he made in his first spell as health secretary back in 2009.

Burnham’s history on this issue is not straightforward. As health secretary in 2009, he floated a significant role for private providers in a future Labour government. After the 2010 defeat, as shadow health secretary, he shifted towards opposing further privatisation. In practice, his earlier vision won out anyway: independent providers delivered more than six million NHS appointments, tests and operations in 2025 alone.

The version of this problem Burnham now inherits is a different beast. Private equity has become the default financial model for large parts of the NHS supply chain – diagnostic centres, dentists, GP surgeries, all increasingly backed by big funds. His one-time leadership rival Wes Streeting was reported to be considering banning “private equity sharks” from healthcare outright. Whether that idea survives contact with a new health secretary remains to be seen.

But banning private equity from the NHS, while a great line on a podium, could be a flawed idea if executed without serious planning.

Why you can’t just switch it off

We aren’t talking about anonymous, shadowy shell companies. PE-backed providers operate under long-term NHS contracts, often with real capital sunk into facilities, staff and infrastructure. Push them out, and government isn’t simply cancelling a subscription – it’s buying them out at market rate, at least in most cases. That’s a major new spending commitment landing on public finances that are already stretched, and every pound of it comes at the direct expense of near-term care.

There’s a second, sharper problem: policy threats have a shelf life before they even become policy. The moment a clear-out looks credible, PE firms start protecting their position – tidying balance sheets, boosting operational efficiency, polishing the numbers for the highest possible exit valuation. A ban announced without teeth doesn’t clean up the house. It fires the starting gun on a fresh wave of consolidation, with taxpayers footing a higher bill than if nothing had been said at all.

Public sentiment against healthcare privatisation is real, but scratch the surface and the actual complaint isn’t usually about ownership structure. It’s simply about the quality of what’s delivered. Safety matters. Profit extraction at the expense of care matters. Most people couldn’t tell you what private equity actually does, but many see the downstream effects on the patient experience, and they don’t like it, particularly when the wider NHS is perceived as being under enormous strain.

That distinction matters enormously for policy design. If the target is patient protection rather than ownership ideology, tighter regulatory oversight of existing PE-backed providers could deliver most of the intended benefit, without government needing to buy out a single contract.

There’s also a definitional problem nobody in Westminster has solved yet. What actually counts as “private equity” here? Fund ownership specifically? Any group structure without clinical specialism? A GP practice owned by someone who isn’t a GP? Until that’s pinned down, it’s impossible to model what any ban would actually hit, or indeed miss.
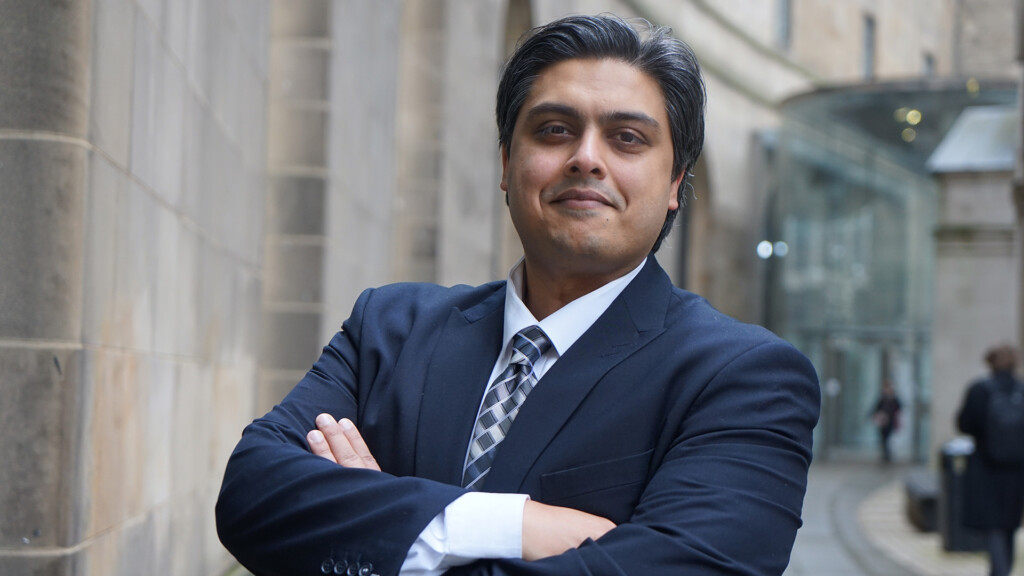
Zohaib Hashim, chief executive of Blackmont Legal.

What happens next, and what to do about it

In the meantime, expect uncertainty to do its own damage. Private care prices are likely to rise. Some of the flexibility currently built into outsourced NHS services may start to disappear as providers hedge against regulatory risk rather than compete for it.

For healthcare businesses already backed by private equity, or weighing it up, the advice is simple: get proper counsel before anything moves. Exit routes in this sector are far more complicated than the headlines suggest, and the gap between a good deal and a bad one almost never comes down to the top-line number. It comes down to structure.

Andy Burnham has built a career on defending public services. Whether he can now design a policy sophisticated enough to protect patients without triggering an expensive, self-defeating exodus of capital. That is the real test of his first months in the job.


Source link

Related Posts

Equity Investments

NervGen to Restate Previously Filed Financial Statements Recognizing Non-Cash Accounting Adjustments

September 26, 2026
Equity Investments

'Don't buy the dividend stocks': Strategist – Yahoo Finance UK

September 25, 2026
Equity Investments

Hot and Cold Stocks of Mutual Funds in August 2026

September 25, 2026
Equity Investments

NZ’s financial adviser news-item centre – Good Returns.co.nz

September 25, 2026
Equity Investments

Dislocation In Market Price Of High Yield Investments

September 25, 2026
Equity Investments

Tempus AI Chief Accounting Officer Sells $529,650 of Stock

September 25, 2026
Add A Comment
Leave A Reply Cancel Reply

Editors Picks

NervGen to Restate Previously Filed Financial Statements Recognizing Non-Cash Accounting Adjustments

September 26, 2026

Macroeconomics Seminar with Gaston Navarro (Federal Reserve Bank Richmond)

September 26, 2026

CARNIVALORATION Q3 2026 Earnings Preview: Recent $CCL Insider Trading, Hedge Fund Activity, and More

September 26, 2026

White Hat Operation Rescues 23K NFTs After Payment Processor Exploit | Social Hacking

September 26, 2026
SUBSCRIBE TO OUR NEWSLETTER

Get our latest downloads and information first. Complete the form below to subscribe to our weekly newsletter.


I consent to being contacted via telephone and/or email and I consent to my data being stored in accordance with European GDPR regulations and agree to the terms of use and privacy policy.

Featured

Sequans Communications sells 456 Bitcoin, plans to liquidate remaining 658

May 28, 2026

LoCorr Expands Team Amid Continued Growth

June 4, 2026

Energy infrastructure repair costs from Middle East war could reach $58 billion, Rystad says

April 16, 2026
Monthly Featured

Best short duration mutual funds to invest in July 2026

August 2, 2026

Weekly links September 6: Lots of goodies that caught my eye while on August break

August 24, 2026

A new gateway to global alternatives

July 1, 2026
Latest Posts

NervGen to Restate Previously Filed Financial Statements Recognizing Non-Cash Accounting Adjustments

September 26, 2026

Macroeconomics Seminar with Gaston Navarro (Federal Reserve Bank Richmond)

September 26, 2026

CARNIVALORATION Q3 2026 Earnings Preview: Recent $CCL Insider Trading, Hedge Fund Activity, and More

September 26, 2026
SUBSCRIBE TO OUR NEWSLETTER

Get our latest downloads and information first. Complete the form below to subscribe to our weekly newsletter.


I consent to being contacted via telephone and/or email and I consent to my data being stored in accordance with European GDPR regulations and agree to the terms of use and privacy policy.

© 2026 Aspire Market Guides.
  • Contact us
  • Privacy Policy
  • Terms and Conditions

Type above and press Enter to search. Press Esc to cancel.

SUBSCRIBE TO OUR NEWSLETTER

Get our latest downloads and information first.

Complete the form below to subscribe to our weekly newsletter.


I consent to being contacted via telephone and/or email and I consent to my data being stored in accordance with European GDPR regulations and agree to the terms of use and privacy policy.