
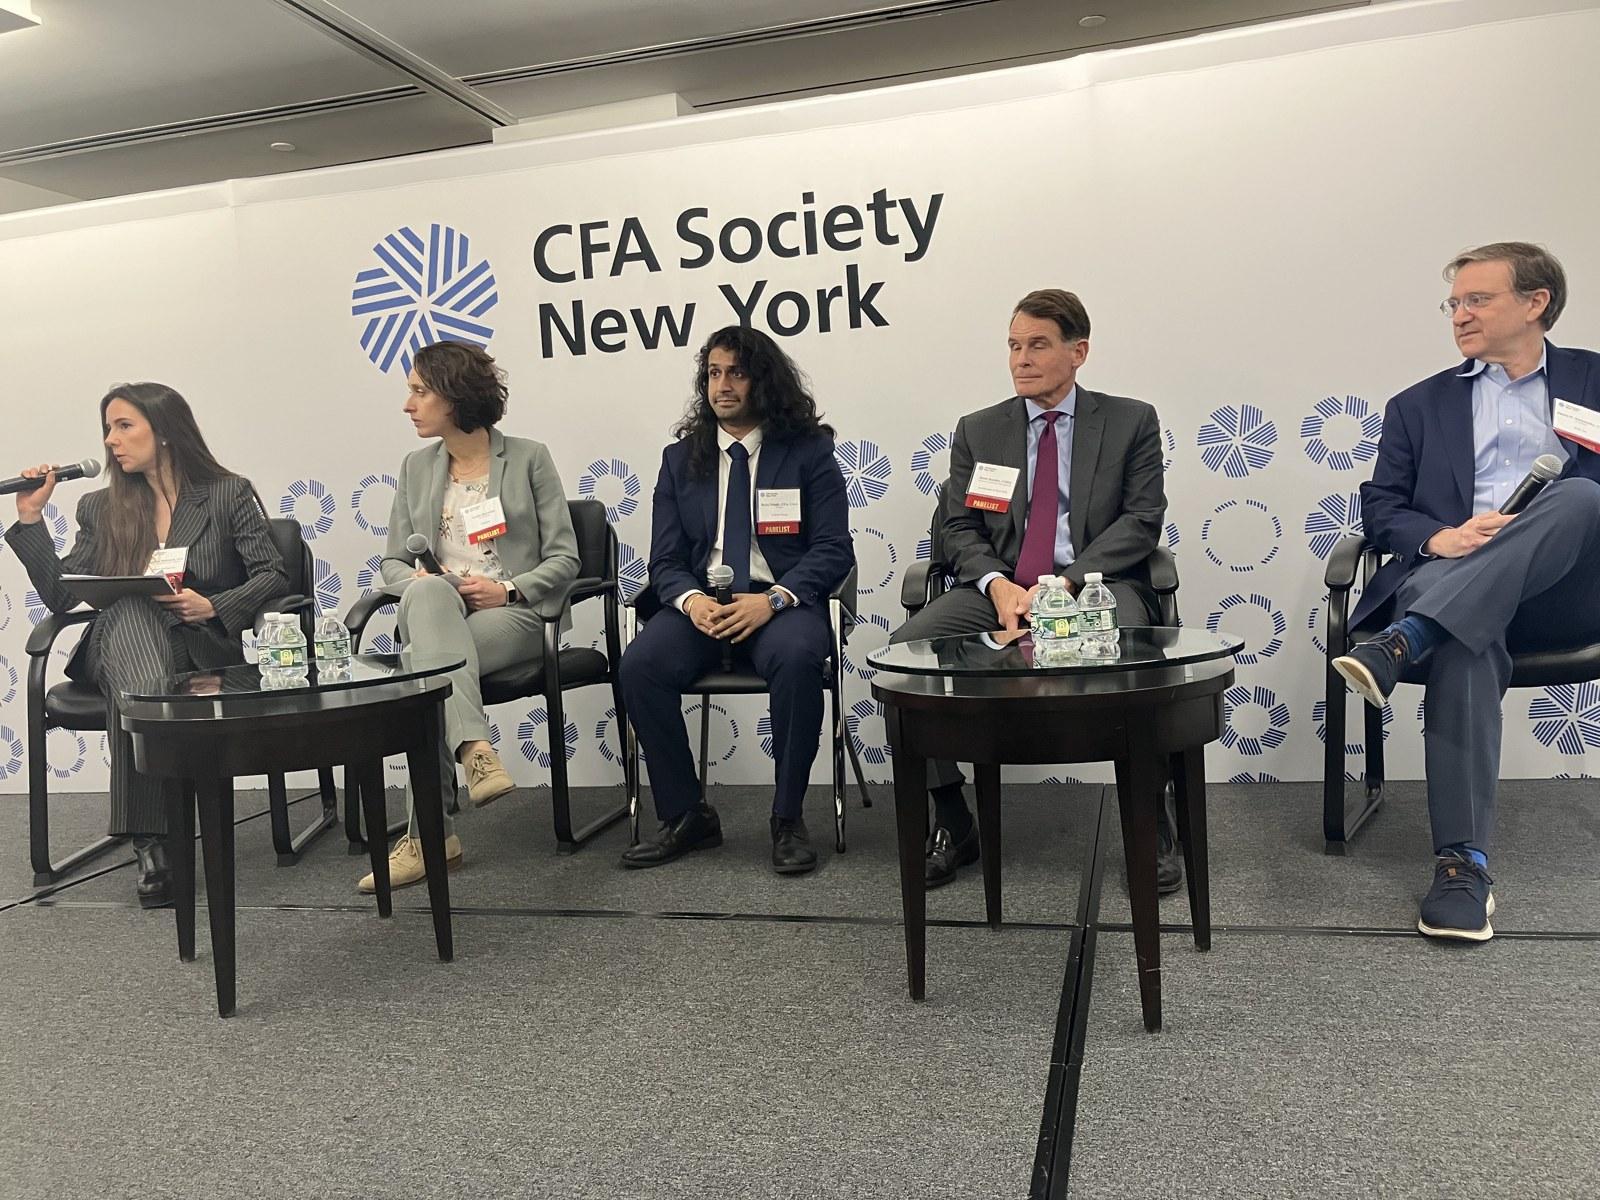
Michael Weinberg’s keynote at CFA Society New York’s “Institutional Exit vs. Retail Entry: Rebalancing the Private Market Ecosystem” event was followed by a panel of four allocators and advisors on how private markets can return cash to existing investors while opening the door to new ones.
The speakers were:
Marion Balazard, CFA (moderator), works in capital formation at Sagard, the alternative asset manager.
Giulia Roverato is a Vice President on Wilshire’s private markets manager research team, which invests for clients and advises institutions across private equity, credit, real assets, secondaries and co-investments. Roverato previously spent four years in co-investments at Adams Street Partners.
Balaj Singh, CFA, CAIA, is an analyst on the multi-asset solutions team at Capital Group, the asset manager with more than $3 trillion in assets, and focuses on private assets.
Scott Snyder, CIMA, is Director of Investment Management at the Archdiocese of New York, overseeing about $3 billion of pension, endowment and foundation assets across 21 accounts.
Jason Samansky, CFA, is a consultant at RVK, Inc., an institutional investment consultant that advises on roughly $4.3 trillion for clients ranging from small religious organizations to $75 billion public pension funds. RVK agreed this month to be acquired by Creative Planning.
Before starting, Balazard polled the room on whether access or liquidity is the bigger issue in private markets right now. The answers that followed suggested it isn’t either-or: exits are stuck, so the industry is looking for new money.
DPI Comes First in Every GP Meeting
Balazard opened with exits, which look hard for private equity funds over the next few years. Roverato said there hasn’t been a meeting in the past 18 months where a GP didn’t state its DPI right at the start, “and if they didn’t, it’s because it was zero.” At one large manager’s annual meeting last year, the GP listed an expected exit date for every portfolio company, including deals it had only just closed and wouldn’t sell for five years. For a small co-investor writing $5 million to $10 million tickets in middle market deals, there is little to manage once a deal is done, so the comfort has to come in the due diligence. Roverato’s investment committee asks questions like: this is a $6 billion enterprise value company, so who buys it? Probably it has to go public, and who can feel confident about the IPO market five years out?